A foreign retirement arrangement may be designed to provide for someone in old age. But does South African law recognise it as a pension? The answer can affect how contributions, investment growth, and benefits are taxed – and what an adviser needs to consider before recommending one.
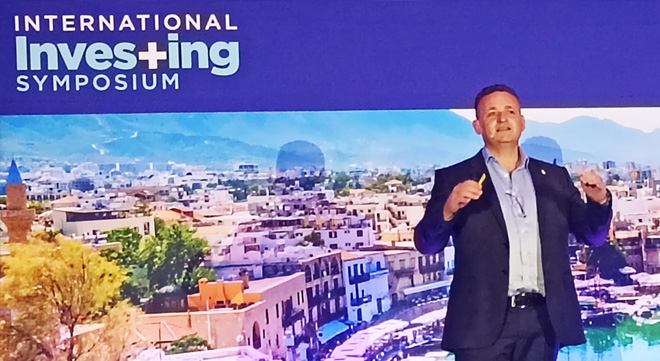
At the International Investing Symposium in Cape Town last month, Rex Cowley, director and co-founder of Overseas Trust & Pension, unpacked the legal and tax framework governing international retirement plans, and the role they can play in cross-border financial planning.
“Complexity isn’t a bad thing; it just means we need to understand complexity in order to be able to deal with it,” he said.
Cowley said clients’ lives are becoming increasingly international. Some are staying in South Africa but moving their money offshore. Others are working abroad while their families and financial commitments remain here. Then there are those who emigrate permanently, and those who return after spending years overseas.
“I’ve seen so many advisers lose clients through immigration when they didn’t need to.”
Four types of South African clients
Cowley grouped South African clients into four broad categories.
The first is the South African resident who intends to stay here but has increasingly international financial needs. Their children may live overseas, for example, or the family may be considering a second residency.
The second is the South African resident working abroad. The client may earn in a foreign currency and build up offshore wealth while still supporting a family, paying school fees, or servicing a mortgage back home. Cowley noted that these clients may spend more than 183 days a year outside South Africa but still be regarded as ordinarily or permanently resident for tax purposes.
The third group comprises South Africans who emigrate with no intention of returning.
The fourth is made up of returning nationals who have spent 10, 15, or 20 years abroad and are now coming home.
Cowley said advisers could be missing opportunities to keep clients who move abroad and to help those who return with their offshore assets and tax planning. A domestic solution may not meet all their needs.
And this is not only a South African trend. He pointed to initiatives by the Financial Planning Standards Board, the Financial Planning Association, and the International Wealth Institute, all of which are putting more emphasis on cross-border financial planning.
“If you don’t do that, you become less relevant to your customer, and therefore someone else will start servicing your customer,” he said.
When is a foreign scheme a pension?
The legal treatment of a foreign retirement arrangement is not determined simply by where it is established or what it is called.
Cowley said advisers need to consider three layers: international law, South African law, and South Africa’s financial-sector regulatory framework.
Where South Africa has a double taxation agreement with the country in which a scheme is established, the agreement’s definition of a pension can determine whether the arrangement is treated as one under South African law. Subject to the relevant conditions, benefits may qualify for an exemption under section 10(1)(gC)(ii) of the Income Tax Act (ITA), particularly where contributions relate to services rendered.
But not every foreign arrangement qualifies. Schemes in Spain, Guernsey, and New Zealand, for example, can have different characteristics.
“You have to start to look at the characteristics of these schemes to see how it actually fits,” Cowley said.
A foreign scheme that meets the relevant criteria may be recognised as a pension fund and exempt from most provisions of the Pension Funds Act (PFA), without having to register as a South African pension scheme. If it is promoted in South Africa, though, the Pension Funds Registrar must be notified and may require registration and annual returns.
The Financial Sector Regulation Act also brings foreign financial products, including foreign pensions, into the regulatory framework. Cowley said a foreign product provider must be regulated under the Financial Advisory and Intermediary Services Act before promoting a product in South Africa. In other words, the provider must qualify as a foreign financial services provider under South African law.
“Critical,” he said, warning that advisers could otherwise contravene FAIS by using services from an unregulated provider.
The legal test for recognising a foreign pension
Cowley explained that determining whether a foreign retirement arrangement qualifies as a pension fund under South African law requires the definitions in the ITA and the PFA to be read together.
The starting point is paragraph (a)(i) of the definition of “pension fund” in section 1(1) of the ITA, which refers to “any pension or dependants’ fund or pension scheme established by law”.
Cowley said two requirements must be met for a plan to qualify as a pension fund under the Act: “The plan must be established by law, and it must be a pension fund or pension scheme.”
A foreign pension or retirement plan established under a system of law meets the first requirement. The second is determined with reference to the PFA, which provides for a statutory pension fund or scheme.
Section 1 of the PFA defines a pension fund organisation and sets out the characteristics an arrangement must have to meet that definition. Cowley highlighted paragraph (a), which refers to an association of persons established to provide annuities or lump-sum payments to members or former members upon reaching their retirement dates, or to their dependants following their death.
Although the definition also includes paragraphs (b) and (c), Cowley said paragraph (a) was the key provision.
“This demonstrates that in order to be a pension fund under the PFA the objective must be to pay benefits only to the member, and only from a specified retirement date with such benefits being lump sums or annuities.”
“These definitions need to be read in conjunction,” he said. Where all these conditions are met, the foreign arrangement qualifies as a pension under South African law because it meets both the ITA and PFA definitions.
Tax treatment depends on the detail
Cowley used SARS Binding Class Ruling 80 (BCR 80), issued in 2022, to illustrate how the tax treatment of a particular foreign pension structure was considered. The ruling deals with the tax implications for resident beneficiaries of a foreign trust, so its findings should not be read as applying automatically to all foreign retirement arrangements.
In the circumstances covered by the ruling, contributions were not subject to donations tax and were not treated as a donation or settlement. The section 7(8) deeming provisions did not apply, allowing investment growth within the scheme to roll up without South African tax.
There was no tax deduction for contributions either. As Cowley put it: “Money in, no tax relief.”
A cash contribution did not trigger tax in the example he discussed, although transferring or selling an asset to fund a scheme could have capital gains tax consequences.
The timing of tax also depends on when a member becomes entitled to the benefits. In the scheme covered by BCR 80, retirement age was 55. Once the member became entitled to the fund, Cowley said, a tax event was triggered. He explained this through the concept of ownership under South African contract law.
“If I have an entitlement to a house, it’s mine. Whether I choose to live in it or not is down to me.”
That does not mean every foreign scheme automatically vests at retirement age. Advisers need to establish when the member acquires an enforceable right to the benefits. How the benefits are paid also matters: under the BCR 80 arrangement, they had to be paid as an annuity and were therefore subject to income tax.
“What are the vesting rules? What are the benefit types? How are benefits paid? All of that becomes important,” Cowley said.
Section 7(1) of the ITA is another important provision to consider. It provides that income is deemed to have accrued to a person even if it has not been paid out but is invested, accumulated, capitalised, credited, or otherwise dealt with on that person’s behalf.
“The purpose of section 7(1) prevents tax avoidance by ensuring that taxpayers cannot defer tax liability simply by keeping income in accounts or arrangements where it is not physically paid out.
“In BCR 80 the client became entitled to the pension at the retirement age which triggered a tax event even though the pension does not pay out… this is because they had an entitlement under the rules of the plan in question.”
Three clients, three planning challenges
Cowley used three case studies to show how an international retirement plan might fit into different circumstances. These were examples of possible planning approaches, not solutions that would work for every client.
The global family
Steven Mackenzie, 54, is a senior executive in Johannesburg earning R2 million a year, with an annual bonus of about R1.5m. His wife is South African, but their children have settled in the United Kingdom and Australia. He plans to retire at 60 and may eventually relocate to Australia.
His South African assets are worth about R18m, including a R12m pension fund, a R5m endowment, and R550 000 in cash. He also owns a UK apartment worth £384 000 and has an Individual Savings Account (ISA) worth £78 000.
Cowley pointed to potential UK inheritance tax exposure on the property, as well as the complications of managing rental income and the difficulty of accessing money tied up in it. He said it could attract UK inheritance tax at 40% above the £325 000 allowance, and he identified the absence of spousal relief in Mackenzie’s circumstances.
His proposed approach was to sell the UK property and ISA and move the proceeds into an international retirement plan. He also suggested partially redeeming the South African endowment but keeping some of it as a domestic investment because Mackenzie still lives in South Africa.
The idea was to build a hard-currency pool for visits to his children or a possible move, while simplifying the estate. “Those assets are highly inefficient,” Cowley said of the UK holdings. The proposed restructuring, he added, would mean: “You’ve cleaned up his affairs. You’ve taken a whole complex leg out of his estate, effectively.”
The returning expat
Tim Mullins, 53, is a telecommunications specialist who has worked in Dubai for 15 years. He earns US$250 000 a year and expects to receive a US$430 000 end-of-service gratuity. His other assets include a US$750 000 offshore bond, a US$350 000 US brokerage account, and US$420 000 in UK cash deposits.
He plans to return to South Africa in five years for semi-retirement. His concerns include moving from a zero-tax environment to South African income tax and estate duty, while keeping his assets offshore and providing for his wife.
“The biggest problem with them, which is also the biggest opportunity, is they have done absolutely no planning,” Cowley said of South Africans working abroad.
His proposed plan was to consolidate assets in an international retirement plan, while keeping the employer gratuity separate from discretionary funds. Cowley said the gratuity, earned for services rendered abroad, could be drawn first and may be tax-exempt in South Africa, subject to the relevant requirements.
Section 10(1)(gC)(ii) exempts from normal tax any lump sum, pension, or annuity received by or accrued to any resident from a source outside the Republic as consideration for past employment outside the Republic.
“Gratuities are specific end-of-service bonus paid in respect of employment and as such, are ‘consideration in respect of services rendered whilst under employment’. As such, where gratuities are paid by an employer into a retirement plan, they qualify under section 10(1)(gC)(ii). If, however, the individual received the gratuity first and then contributed it to the foreign plan, it would not qualify.”
He also discussed what happens when Mullins returns to South Africa for tax purposes. Cowley said the date on which tax residency resumes is important because, in his proposed approach, the value of the client’s worldwide assets would be established at that point. Growth accumulated before the return could then be treated as capital, potentially allowing it to be drawn without tax if the scheme permits lump-sum benefits rather than requiring an annuity. The treatment would depend on the scheme and the individual’s circumstances.
The pre-emigration window
Elani Van Wyk, 49, is a widowed chartered accountant with two teenage children. She plans to take up a senior position in Portugal in six months. Her assets include a R20m domestic South African trust established after her husband’s death, a R4m endowment, and a R2.5m retirement annuity.
Cowley said leaving these assets in South Africa could create complications around trust administration and succession across different jurisdictions. The RA and endowment might also not be the most suitable arrangements once she is living in Portugal.
His proposed approach was to establish a foreign trust and an international retirement plan, with the foreign trust appointed as beneficiary of the current South African trust. Cowley said South African domestic trusts have been able to appoint foreign trusts as beneficiaries for the past three years, subject to exchange-control requirements.
In 2023, the South African Reserve Bank’s Financial Surveillance Department (FinSurv) issued Exchange Control Circular 3 of 2023, amending the Currency and Exchanges Manual for Authorised Dealers (AD Manual) to permit certain transfers from South African inter vivos trusts to offshore beneficiaries, including offshore trusts, subject to strict SARS and SARB compliance. Both SARS and SARB have published guidance on what is required from compliance and approval.
He described the process of making distributions to offshore beneficiaries from South African trusts as “very, very difficult”.
He also proposed cashing in the endowment and transferring the proceeds offshore using the applicable exchange-control allowance and funding a foreign retirement plan.
FSCA Communication 1 of 2023 (RF) sets out the enhanced online submission process for section 14 applications under the PFA, with specific provisions for transfers to insurers or foreign funds.
“This must not be confused with a tax-free transfer, as the transfer may attract tax depending in the nature of the fund being transferred. But tax aside, transfer to foreign funds and insurers are permitted under the Act, as confirmed.”
Once Van Wyk becomes non-resident, her RA could potentially be transferred under section 14 or cashed in provided the three-year lock in had been met and fund the foreign pension.
The plan would provide a way to hold hard-currency assets and plan for the children’s succession needs. Cowley said foreign pension schemes may have provisions to accommodate the tax rules of countries such as Portugal, Australia, New Zealand, Spain, and the UK, but the treatment in the destination country would still need to be considered.
An additional tool, not a universal answer
Cowley outlined six areas in which international retirement plans may be useful: asset protection, taxation, investment and currency flexibility, probate and succession, wealth accumulation, and access to benefits.
He said Guernsey plans can offer ring-fencing against political risk, changes in government policy, and third-party claims. He also described tax-efficient investment growth, international investment without exchange-control or asset-swap restrictions, and succession through a trustee rather than an executor.
Other features are an unconstrained funding environment with no funding limits, the ability to consolidate foreign assets and hold inheritances or employer gratuities, and access to benefits from age 50. Depending on the plan, members may be able to choose annuities or lump sums of up to 100% of the plan’s value. These are features Cowley attributed to the plans offered by his firm, rather than a description of every foreign retirement arrangement.
His advice was not that every client needs an international product. “You probably don’t need too many of them,” he said, identifying life insurance, endowments, and pensions as the main categories to consider.
Advisers who understand the legal, regulatory, and tax implications may be better placed to keep clients who move abroad and help those who return.
“They will differentiate you from your peers if you can advise on an international basis,” Cowley said.
Disclaimer: The views expressed in this article are those of the speaker and do not necessarily reflect the views of Moonstone Information Refinery. The information is intended for general information purposes and should not be construed as financial, tax, or legal advice. Readers should seek independent professional advice relevant to their individual circumstances.