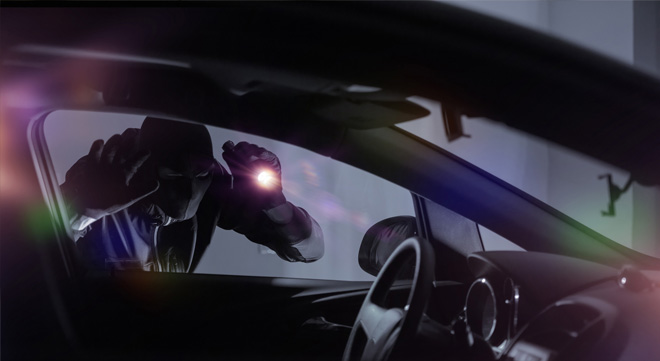
A financial services provider was ordered to pay R786 300, plus interest, after it could not prove that a client had been informed of a tracking-device requirement on her Toyota Prado, which was later stolen.
FAIS Ombud Advocate John Simpson discussed the case when he presented the Office’s 2025/26 Annual Report. It illustrates the potential cost of failing to demonstrate that a client was properly informed of a material insurance requirement.
The case is among the summaries now available on the FAIS Ombud’s website. Simpson said the searchable summaries are intended to help consumers and financial services providers understand how the Office assesses complaints and resolves disputes. New summaries are being added regularly.
The evidence behind the decision
The complainant’s Toyota Prado was stolen, and the insurer rejected the claim because the vehicle did not have the required tracking device installed.
The financial services provider, which was the respondent in the Ombud proceedings, said it had sent multiple emails to the complainant’s email address. The complainant denied receiving them.
The Ombud asked the provider for evidence that the emails had been sent, delivered or read. It could not produce supporting records from its systems. Nor could it show that it had followed up with a telephone call to check whether the complainant had received the information.
Simpson said the provider had to demonstrate that it had complied with its obligations under the General Code of Conduct for Authorised Financial Services Providers and Representatives.
“The code requires financial service providers to keep records of everything it does, to have records of having advised and informed complainants of material changes to the policy,” he said.
He described the tracking-device requirement as “an extremely material requirement”.
Without evidence that the client had been properly informed, the Ombud could not find in the provider’s favour. Simpson said: “On a balance of probabilities, we were unable to find that the complainant was properly informed of this requirement.”
The Ombud upheld the complaint and ordered the provider to pay the vehicle’s sum insured of R786 300, plus interest. The determination was subsequently filed as an order of court.
Why follow-up matters
Simpson said tracking-device disputes were a recurring issue for the Office. Where an insurer requires a tracking device, failing to meet that condition can put a client’s cover at risk.
He urged brokers and financial advisers to inform clients of tracking requirements and take reasonable steps to ensure they understand what is needed.
“Obviously, at the same time, encourage advisors to make sure that they inform their clients properly and follow up to determine whether the client actually knows about it; it’s extremely important,” he said.
The case shows why providers need more than an assertion that an email was sent. They should retain records of important communications and be able to demonstrate that they took reasonable steps to inform clients of requirements that could affect their cover.
Consumers should check their cover
Simpson also urged consumers, particularly owners of Toyota vehicles, to contact their advisers to check whether their policies contain tracking-device requirements and whether their vehicles meet them.
“We really strongly want to encourage consumers to check with the advisors, call the advisor, email them, ask them, ‘Am I covered? Do I have the required tracker?’” he said.
He said it was better to confirm the requirements before a loss occurred than to discover a potential gap in cover after a vehicle had been stolen.