Insurer cannot diagnose non-disclosure with hindsight
The doctor’s medical knowledge did not allow Discovery Life to rely on developments he could not reasonably have known about when applying for cover.
The doctor’s medical knowledge did not allow Discovery Life to rely on developments he could not reasonably have known about when applying for cover.
A fraud-related cancellation almost 15 years earlier cost the policyholder his tornado claim because he failed to disclose it when applying for cover.
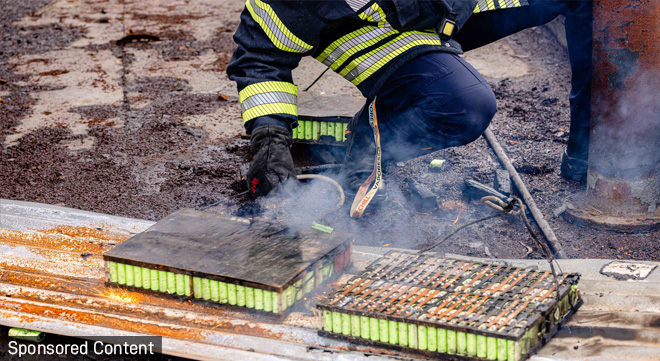
About 24% of Fire Ops SA’s structural-fire call-outs since January were linked to alternative-power equipment.
A new GoTyme-powered banking service is part of a broader strategy to build closer customer relationships, even as investment in future growth weighs on earnings.
Stronger South African margins drove group earnings higher, while natural peril and CTP claims weighed on Youi’s rapidly growing Australian business.
Discovery Bank has reached profitability, while Vitality, Invest, and Insure are making larger contributions as the group gradually broadens its earnings base.
An impaired credit record and frequent switching may combine to make affordable short-term insurance more difficult to obtain.
The insurer’s differentiation between co-owners was rationally connected to its risk-management objectives.
Evolving buildings and technologies are complicating structural fires, increasing the importance of prevention, resilience, municipal capacity, and effective risk transfer.
A policyholder’s godfather was recorded as her father despite the adviser knowing the true relationship, leading to a ruling that the insurer must pay the claim.
A routine interaction for an insurance professional can be a crisis for the person on the other side, making empathy a practical part of the job.
An NFO case highlights the requirements of Rule 17.8.6 and the consequences when an insurer fails to communicate during a prolonged claims process.
The Appeal Tribunal found that an undisclosed diagnostic test was not material to the insurer’s assessment of the risk and ordered the claim to be paid.
The NFO found that a property owner could not avoid responsibility for an increased risk where poor construction, electrical defects, and tenant conduct contributed to the loss.
CDH says the decision highlights the risks for businesses that incorporate cover or risk-transfer arrangements into broader commercial offerings.
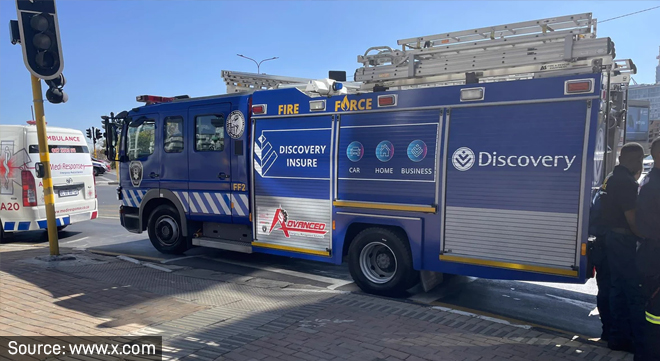
Private firefighting networks, connected smoke detectors, and faster emergency response are giving insurers new ways to limit losses before flames engulf a home.
Old Mutual Insure says demerit points could eventually influence underwriting, but only if they prove to be a reliable predictor of insurance risk.