Private capital firms in Southern Africa raised R22 billion in 2025, the second-highest annual total in a decade. Yet investment value fell 16% and deal volumes dropped 18%, leaving a widening gap between the capital flowing into the industry and the money being deployed.
The SAVCA Private Capital Industry Survey 2026, compiled by the Southern African Venture Capital and Private Equity Association (SAVCA) with EY-Parthenon, records a 162% increase in fundraising from R8.4bn in 2024. This came despite a decline in global fundraising.
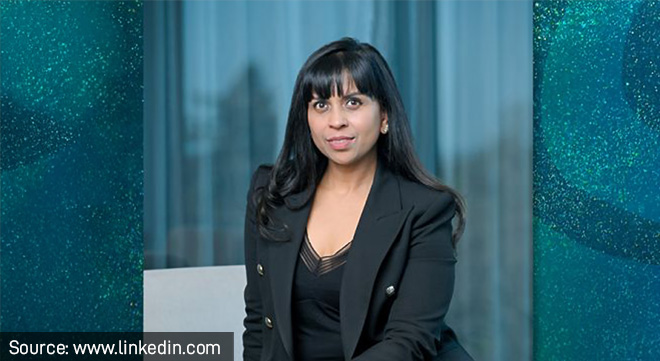
SAVCA chief executive Anusha Naidu (pictured) describes a more supportive economic environment in Southern Africa, with lower inflation, easing interest rates and modestly improved growth. Global trade tensions, geopolitical uncertainty and shifting market conditions nevertheless contributed to a more cautious investment environment.
South African investors contributed 55% of funds raised, their highest share in four years. Pension and endowment funds were the largest disclosed domestic source, contributing R4.4bn, up from R1.6bn in 2024.
Fundraising rebounds as investment slows
Eighteen firms raised capital in 2025, compared with 13 the previous year. Investment value, however, fell from R26.6bn to R22.4bn, while the number of investments, excluding Business Partners, declined from 228 to 186. Despite the slowdown, investment value remained above the ten-year average of R21.7bn.
New investments accounted for R15.3bn, down from R19.7bn in 2024. Follow-on investments edged up from R6.9bn to R7.1bn, increasing their share of total investment value from 26% to 32%.
Mid-market firms, with funds under management (FUM) of between R2bn and R5bn, increased their share of deal volume from 14% to 37%. Generalist funds accounted for 59% of investment value, up from 41% in 2024.
Infrastructure and energy reshape portfolios
Infrastructure, energy and related funds continued to attract most of the capital raised, although their share fell from 71% in 2024 to 62% in 2025.
Their share of industry FUM moved in the opposite direction, increasing from 29% to 42%. Generalist funds’ share of FUM fell from 54% to 43%.
Energy accounted for 15% of deal volume, up from 10% in 2024, and energy, education, real estate and infrastructure led investment by value. The increase in education investment was largely attributable to one manager, rather than a broad-based shift across the industry.
Funds under management decline in rand terms
Industry FUM fell by 3%, from R233.3bn in 2024 to R226.4bn in 2025. In US dollar terms, it rose by about 11%, reflecting the appreciation of the rand against the dollar.
A like-for-like comparison of firms that participated in both years showed a 5.8% decline in FUM, although 42% of those firms recorded growth.
Undrawn commitments, or dry powder, fell from R48.7bn to R45.4bn. Despite the 7% decrease, the remaining commitments were still roughly twice the value invested during 2025, leaving capital available for future deployment.
Exits improve, with trade sales leading
Exit proceeds rose 19%, from R17.1bn in 2024 to R20.3bn in 2025. The number of exits remained unchanged at 52, but the mix shifted towards trade sales, which increased from 15 to 27 and generated R5.8bn in proceeds.
Exits to other private capital firms and financial institutions fell from 19 to five. Infrastructure and energy funds accounted for 52% of exit proceeds, compared with less than 20% in each of the previous three years.
For exits where figures were disclosed, the proceeds-to-cost ratio improved from 1.5 to 1.6 times. Write-offs increased from eight to nine.
Naidu says stronger exit activity signalled improved market conditions. Trade sales had re-emerged as the leading exit route, while public markets had reopened for larger, high-growth private capital-backed businesses. These developments, she says, provide investors with greater flexibility and create “pathways for capital to be recycled into new opportunities”.
Portfolio-company performance is mixed
Employment grew at 70% of portfolio companies between 2023 and 2025, while 30% reduced their headcount. Among companies that expanded their workforces, the weighted average annual employment growth rate was 16%, with combined employee numbers rising from 83,907 to 111,969.
Results varied by sector. About a third of retail companies and 34% of agriculture and agri-processing companies reported declining headcount.
Revenue growth also moderated. The proportion of portfolio companies recording compound annual revenue growth above 5% fell from 66% in the previous survey to 56%, while 26% reported declining revenue.
For earnings before interest, taxes, depreciation and amortisation (EBITDA), 55% recorded compound annual growth above 5%. A further 37% reported declining EBITDA, compared with 35% in the previous survey.
Technology rises up the agenda
Technology transformation became a higher priority for private capital firms, with the proportion identifying it as a key priority rising from 11% to 40%.
Spending on artificial intelligence (AI), however, remains limited among local firms. Only 7% allocated more than 25% of their IT expenditure to AI, compared with 48% globally, according to the survey.
Geopolitics remained the leading concern among firms, while technology disruption was identified as the fastest-rising risk.
Transformation advances, but representation remains uneven
Fund managers with a Level 1 B-BBEE rating accounted for 47% of FUM, up from 40% in 2024. The proportion of private capital firms with more than 50% black ownership rose from 61% to 67%, while the share with majority-black management increased from 72% to 83%.
Firms with more than 30% black female ownership increased from 31% to 38%.
Progress in gender representation was less consistent. Female representation improved in deal teams and portfolio-company boards but declined on fund-manager boards for the second consecutive year. The promotion of female board members also remained low, according to the survey.
ESG data remains a challenge
The proportion of firms reporting a “very positive” ESG impact on exit outcomes tripled, from 5% to 15%.
Naidu says private capital firms are increasingly focusing on operational value creation, transformation, talent development, governance, technological innovation and portfolio resilience. She also points to the need to improve the quality of ESG and impact data, which remains a challenge for assessing progress across portfolio companies.
Outlook remains positive
Despite slower investment activity, firms expressed greater confidence in the industry’s prospects. Eighty-eight percent expected FUM to grow at an accelerated or moderate pace over the next three years, up from 79% in the previous survey. Of these, 46% anticipated accelerated growth and 42% moderate growth.
Allocators were more cautious: 71% expected moderate FUM growth, while 29% anticipated that their FUM would remain at similar levels.
Views on fundraising in 2026 also differed. Fifty-seven percent of allocators expected fundraising to increase, compared with 40% of private capital firms.
Second-generation funds ranked ahead of first-time funds among local allocators’ priorities. Private equity, real assets and infrastructure were the leading types of private capital allocation, while interest in private credit, venture capital and funds of funds was also growing. Technology was allocators’ leading sector priority, followed by infrastructure.
Naidu says continued collaboration between investors, fund managers, policymakers and regulators will be needed to create an environment that supports investment, innovation and growth. In her words, the opportunity is to “translate confidence into action” and help build a more competitive, inclusive and prosperous economy.
Note: The survey is based on voluntary participation and is not a comprehensive census of the Southern African private capital industry. Its findings reflect information supplied by participating firms and allocators; the underlying data has not been independently audited or verified in full.