The AI boom is generating extraordinary revenue, but some of the biggest players are also funding the businesses buying their technology. Morningstar Investment Management says these increasingly intertwined relationships make it harder for investors to judge how sustainable the industry’s earnings really are.
Chipmakers, cloud providers, and artificial intelligence developers are not simply riding the same wave of growth. They are helping to finance one another.
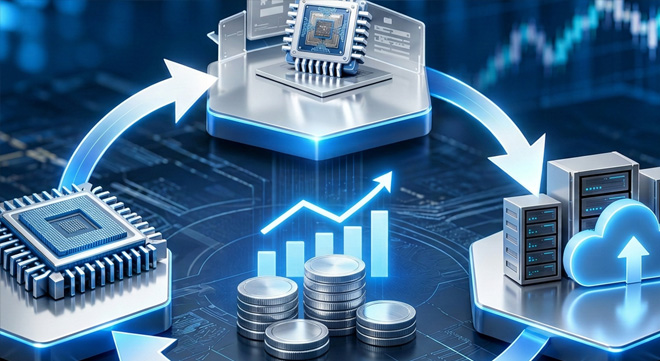
The companies building the infrastructure for AI are investing in the businesses using it. Those businesses, in turn, spend billions on the chips and cloud computing capacity supplied by their investors. Revenue, investment, and demand are becoming tightly interwoven.
Presenting Morningstar’s 2027 Investment Outlook on 18 November 2026, Sean Neethling, head of investments at Morningstar Investment Management South Africa, said investors needed to look beyond the headline earnings of individual companies and examine the relationships driving growth across the sector.
“We do think that a lot of these companies are pretty much priced for perfection. Everything needs to go right in order for that price to be justified,” he said.
When customers are also investors
Neethling used the relationships between semiconductor manufacturers, cloud providers, and AI developers to illustrate how closely connected the industry has become.
Chipmakers depend on a relatively small number of large cloud computing providers, including Alphabet, Amazon, and Microsoft. These hyperscalers supply the computing capacity used by AI developers, which rely on chips and cloud services to train and operate their models.
The financial relationships are just as interconnected.
Microsoft owns roughly a quarter of OpenAI, while Amazon and Alphabet have meaningful stakes in Anthropic. Both are also major cloud providers to the AI company.
Nvidia has taken equity positions across the AI infrastructure and development chain. It completed a $2-billion investment in CoreWeave in January 2026 and made investments of $30bn in OpenAI and $10bn in Anthropic. These investments sit alongside commercial relationships: CoreWeave uses Nvidia GPUs in its cloud infrastructure, while OpenAI and Anthropic are developing and running AI models using Nvidia technology.
In other words, some of the companies supplying the technology are also financing the businesses buying it.
“Money goes in as equity and comes back as spending on clouds and chips,” Neethling said.
The pattern repeats across the supply chain. Chipmakers rely on a handful of hyperscalers; hyperscalers depend on a relatively small group of AI developers; and those developers need a limited number of suppliers to provide the infrastructure and computing power they require.
This creates a web of dependencies that can make the sector look more robust while spending continues to flow. But it also means that trouble at one company can travel quickly through the ecosystem.
If an AI developer struggles to generate enough revenue, it could cut its spending on cloud services and computing infrastructure. Its suppliers would feel the effect, while investors in the developer could also face weaker returns.
The issue is not simply whether the revenue is real. It is how much of it depends on continued investment and spending by other companies within the same network.
Neethling said the arrangement worked while companies continued spending and revenue and cash flow kept moving through the system.
“If any link in this chain breaks, investors are likely to be left with a lot of disappointment,” he said.
He does not expect the industry’s development to follow the smooth trajectory that market pricing appears to assume.
“We don’t think that it’s likely that it will play out as linearly as what the market is pricing,” he said.
The capital cycle is turning
There is another question hanging over the sector: how long can today’s exceptional returns last?
Strong demand for chips and computing capacity has allowed some semiconductor companies to generate extraordinary profits. Neethling said margins and earnings at several major businesses had climbed well above what Morningstar considers normal.
Those returns are attractive – not only to investors, but to competitors.
In a classic capital cycle, high profits draw in new investment and new entrants. As capacity expands and competition intensifies, pricing power can weaken, and margins come under pressure.
That process may already be gathering momentum. Significant additional chip and data-centre capacity is expected to come online over the next two years. If supply catches up with demand, companies may struggle to sustain their current margins.
The scale of investment is also running ahead of certainty about the eventual commercial returns. Demand for computing power is strong, but that does not automatically translate into equally strong, durable revenue from AI products and services.
Neethling pointed to companies generating lower cash flows and taking on more debt, even as spending across the AI ecosystem remains high. The ability to turn adoption and infrastructure investment into sustainable revenue is still being established.
Technology is moving at a pace that complicates the investment case further. New AI models are emerging regularly, raising questions about how long today’s products, chips, and infrastructure will remain competitive. Rapid advances could shorten the useful life of existing technology and require another round of substantial investment.
Regulation, data privacy, and geopolitical competition between the United States and China add further uncertainty.
A powerful opportunity – with a lot priced in
None of this means the AI opportunity is disappearing.
Neethling acknowledged the strength of the positive investment case: highly profitable companies, demand for computing power that still exceeds supply, significant barriers to entry, and the growing use of AI in business.
The technology requires substantial capital, specialised expertise, and access to infrastructure. Those barriers make it difficult for new players to compete, while established companies are already benefiting from adoption across business operations.
But strong demand and impressive earnings do not make every valuation attractive. Nor does the long-term potential of AI guarantee that today’s market leaders will maintain their growth rates and margins.
More capacity could bring competition. New technology could disrupt existing business models. And companies that depend on continued spending elsewhere in the ecosystem could find themselves exposed if that spending slows.
Investors are having to weigh the enormous potential of the technology against the assumptions already built into share prices.
AI exposure is not confined to technology shares
The influence of AI on investment returns stretches well beyond the companies most obviously associated with the technology.
Neethling noted that AI and technology businesses had contributed significantly to returns in emerging markets, particularly through semiconductor manufacturers in South Korea and Taiwan. US small-cap shares had also benefited from exposure to the theme.
That has implications for portfolio diversification. Investors holding shares across different regions and market segments may have more exposure to the same AI investment cycle than they realise.
A portfolio can look diversified by geography or company size yet still depend heavily on a relatively narrow group of industries and businesses to drive returns.
How Morningstar is positioning portfolios
Morningstar is not advocating that investors abandon technology shares. The focus is on understanding what they own, what they are paying for it, and how much of their portfolio depends on the sector’s continued success.
At the time of the webinar, the investment team was approximately 5% underweight US technology.
Neethling said a market correction could provide an opportunity to reduce that underweight, but any adjustment would depend on a careful assessment of the companies involved.
“We look very deliberately in terms of once we basically narrow our underweight, how do we do it? And that’s built on a disciplined framework of making sure we understand what’s driving revenue, cash flows, and margins,” he said.
That means looking beyond the excitement around AI to the underlying economics: where revenue comes from, how much cash a business generates, what returns it earns on its investments, and whether those returns can withstand greater competition.
AI may continue to transform industries and drive investment returns. But the fortunes of the companies building that future are increasingly tied together – and investors need to understand what happens if the money stops going round.