Artificial intelligence could put basic financial advice within reach of people who have never been able to afford it. It could spot patterns in transactions that humans might miss, help to detect fraud earlier, and make financial education available in local languages through familiar platforms.
It could also get things badly wrong.
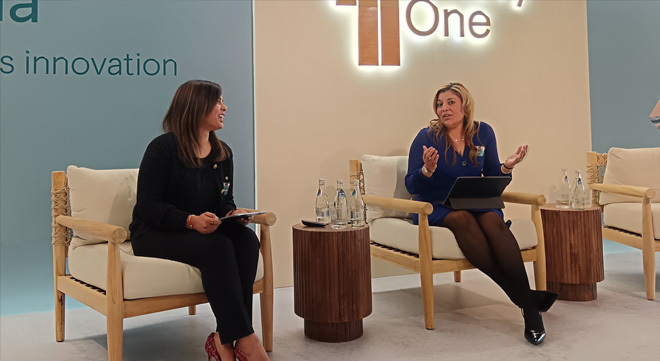
Khadeeja Bassier, chief operating officer at Ninety One, and Farzana Badat, deputy commissioner at the Financial Sector Conduct Authority, discussed the opportunities and the risks of AI in financial services at Ninety One’s Beyond Alpha event this month.
Badat wanted the discussion to go beyond the familiar questions about jobs, deepfakes, and automation. She was particularly concerned about how AI is changing the way people think.
She described this as a change in our “cognitive endurance”. Previous technologies changed how people accessed information, but there were still shared reference points. AI adapts its response to the person using it, meaning two people can ask the same question and receive different answers, tailored to their language, tone, and apparent preferences.
Badat warned that this can create a highly personalised loop that reinforces existing biases and tastes.
The concern is what happens when people start outsourcing the thinking itself. She argued that people need “cognitive friction” – the process of working through information, questioning it, and reaching a conclusion.
She described AI as a “cognitive amplifier”: it can make someone who already has a high degree of agency more capable, while making someone who simply waits for an answer more dependent on the technology.
When the machine sounds convincing
The problem becomes more immediate when AI is dealing directly with consumers.
Badat said an AI system can produce an answer that sounds completely convincing and still be wrong. A chatbot could hallucinate a regulatory requirement or a policy exclusion, for example. A consumer may have no reason to question the answer, particularly if it sounds authoritative.
For a vulnerable consumer, the consequences could be a financial loss or penalty.
“So, how do you regulate for something like that?” she asked.
Badat also pointed to vulnerabilities that a human adviser may identify but a chatbot may not. A system might calculate someone’s debt accurately while missing emotional distress or cognitive decline.
AI can help with the information. It cannot necessarily understand the circumstances in which a financial decision is being made.
Who is accountable?
Accountability becomes more complicated when one company develops the AI, another integrates it, and a financial institution deploys it.
Badat described different “spheres of accountability” between the developer of a foundational model, the system integrator, and the institution using it.
The institution may not have built the model, but it chose to put the technology in front of its clients.
“Ultimately though, if you are an institution that chooses to deploy the AI, your board and your senior leadership need to be held accountable for the outcome,” she said.
That requires more than having a person somewhere in the process. The institution needs to be able to show that there was human oversight and that the outcome was considered before it affected a customer.
Bassier similarly argued for keeping “humans in the loop”, particularly in financial services where regulatory requirements demand accountability.
The technology may come from somewhere else. The decision to use it does not.
An adviser in every pocket?
There is a considerable upside if AI can be used safely.
Badat suggested that basic financial advice could become far more accessible because a chatbot can operate around the clock and at a fraction of the cost of human advice.
For someone who has never been able to afford an adviser, it could provide a first point of contact with the financial system.
She also described a more everyday use: an AI system noticing that someone’s cash flow has improved and prompting them to consider putting some of the extra money into savings or an investment.
But the same system may see the numbers without understanding the person behind them. It may know that a client has debt without recognising that they are experiencing emotional distress or cognitive decline.
That is where Badat sees human advice retaining an important role.
The data underneath the machine
Bassier focused on the importance of data.
“There is no AI strategy without a data strategy,” she said.
For a financial institution, this is not simply about having enough information to feed a model. Bassier pointed to the sector’s fiduciary responsibility to produce outcomes that are accurate, consistent, and repeatable.
That can sit uneasily with the probabilistic nature of AI. Institutions need to understand the information being fed into a model, the context in which it operates, and whether its results can be relied on consistently.
Privacy complicates the picture further.
Badat said privacy has traditionally been treated as an individual right: if you do not consent to someone accessing your data, they should not have it.
AI is beginning to break down that boundary.
“Actually, right now, it doesn’t really matter whether you say you can see my data or not,” she said.
Her point was that information about you does not necessarily have to come from you. If someone cannot obtain your private information directly, they may be able to obtain pieces of it from people around you and use those pieces to build a picture of you.
Information shared by friends or family, combined with other data, could reveal things an individual has never explicitly disclosed.
For Badat, the question is therefore less about whether someone can access your data and more about what they are going to do with it.
That becomes particularly important in financial services, where information assembled from different sources could potentially be used to determine whether someone gets an insurance policy, a loan, or another financial product.
The danger of everyone using the same model
Badat also warned about what happens if financial institutions begin relying on a small number of AI models.
She identified two risks.
The first is financial exclusion. If models are based on traditional approaches and do not understand local circumstances, they may simply reproduce existing assumptions about who is a suitable customer.
The second is “herding behaviour”. If institutions rely on similar models, they could end up making similar decisions because they are working from similar assumptions.
A model developed for another market may not understand the way South Africans earn, spend, borrow, or interact with financial institutions.
Building for South Africa
South Africa’s young, increasingly digitally native population could be an important advantage as AI develops. But there is a risk that countries in the Global South become “data colonies” – supplying the data and labour that help to build AI systems while the technology and much of its economic value are developed elsewhere.
For the financial sector, that question goes beyond where a model was built. A system trained primarily on data and behaviours from other markets may not understand how South Africans communicate, earn, spend, or use financial services.
The opportunity is to build technology around those realities rather than simply import it.
Local languages are one example. Badat pointed to automatic speech-recognition technology that could be developed to work properly in South African languages, rather than relying on systems designed primarily around English. The point is not simply to translate an existing technology, but to build systems that work in the context in which they are going to be used.
The same thinking applies to financial services: AI tools can be designed around how South Africans interact with financial institutions, rather than expecting consumers to adapt to systems developed for another market.
There is a skills question alongside this. South Africa needs people who can build and evaluate AI, not simply use it. That includes technical skills such as prompt engineering and API integration, but also an understanding of the ethical questions that arise when these systems are put to work.
Bassier pointed to education as part of that shift. Rather than treating AI primarily as something to police – for example, through plagiarism detection – institutions need to think about how people will work alongside it and how the technology can be made relevant to local circumstances.
The economic opportunity is not simply having a young population that adopts AI quickly. It is whether that population becomes part of the people building, testing, and shaping the technology.
A way into the financial system
Badat’s longer-term vision for AI was not limited to making financial services more efficient.
She pointed to South Africa’s large informal economy and the people who struggle to fit conventional financial models.
Traditional credit assessments often depend on formal employment, documented income, and established credit histories. AI could potentially use transaction histories, cash-flow patterns, and digital payment trails to develop alternative profiles for people who do not fit those models.
Instead of asking only whether someone has a conventional credit history, a financial institution could potentially build a picture of how that person’s finances work.
The same technology could be used for financial education. Badat envisaged conversational financial services operating in local languages and through platforms such as WhatsApp, allowing someone who would never sit down with a financial adviser to have a basic financial conversation through a platform they already use.
There are similar possibilities in fraud detection. Rather than identifying fraudulent activity after money has left an account, AI could potentially identify patterns, cash flows, and connections associated with fraud earlier.
Where the machine stops
For all the possibilities discussed, there was a point beyond which Badat did not want the technology to go.
The question was what should remain “irreducibly human” as more financial decisions are supported by machines.
Her answer included accountability, empathy, creativity, and moral judgement. It also included deciding what an organisation means by value. Is it profit? Sustainability? Inclusion?
An AI system can optimise towards a target that people give it. It cannot decide whether that target is the right one or take responsibility for the consequences.
Badat drew the line here: “Never allow the AI to be the final decision-maker for something that materially affects not just a consumer but even a financial institution.”
That leaves plenty of room for AI. It can analyse information, identify patterns, support advisers, improve processes and potentially open financial services to people who have been left outside the formal system.
But if the decision affects a client materially, someone still needs to own that decision. And that person cannot be the machine.