A beneficiary who challenged the rejection of a life insurance claim ultimately secured payment of the policy proceeds after the Appeal Tribunal found that the deceased’s previous skin cancer and alleged lung condition were not material to the insured risk.
The dispute travelled through the ombud process and the High Court before reaching the Appeal Tribunal, which overturned the earlier decision and ordered the insurer to pay the claim with interest. The case was included in the 2025 annual report of the National Financial Ombud Scheme (NFO).
The deceased was insured under a life policy marketed by Standard Bank and underwritten by Liberty Group. The policy commenced on 1 November 2019, and the insured died on 27 June 2021.
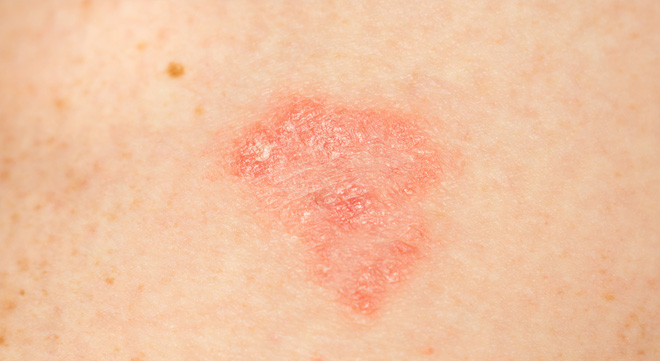
Liberty rejected the claim on 8 November 2021, citing the insured’s failure to disclose a history of basal cell carcinoma and an alleged lung condition. The insurer argued that these omissions materially affected its assessment of the risk.
The beneficiary disputed that the information was material.
Ombud finds against beneficiary
An adjudicator initially dismissed the complaint in a provisional ruling.
The adjudicator considered the test for materiality in rule 21.2 of the Policyholder Protection Rules. It provides that a representation or non-disclosure is material if a reasonable, prudent person would consider that the information should have been disclosed so the insurer could form its own view about its effect on the risk.
The adjudicator found that a reasonable, prudent person would have disclosed the insured’s medical history, including the removal of malignant tumours and his self-reported lung condition.
Another adjudicator reconsidered the matter and upheld the decision in a final ruling. Because the insurer said it would not have issued the policy had the information been disclosed, the final ruling found that it had been entitled to repudiate the policy.
The beneficiary applied for leave to appeal, but the application was dismissed by the Ombudsman for Long-term Insurance (OLTI) in July 2023.
The beneficiary then approached the High Court to challenge the refusal of leave to appeal. On 6 June 2025, the Gauteng High Court set aside that decision, allowing the matter to proceed to the Appeal Tribunal. The Court’s order concerned the refusal of leave to appeal and did not itself decide whether the insurance claim should be paid.
Tribunal reconsiders medical evidence
After a hearing, the Appeal Tribunal reached a different conclusion from the adjudicators.
It found that the insured’s basal cell carcinoma had been completely excised, posed no threat to his longevity, and did not amount to a material non-disclosure affecting the insurer’s assessment of the life risk.
The Tribunal’s approach was consistent with the principle confirmed by the Constitutional Court in Swanepoel NO (Executor in the Estate Late Mignon Adelia Steyn) v Profmed Medical Scheme: only information material to the assessment of the risk must be disclosed.
The Tribunal also rejected the insurer’s reliance on the alleged lung condition. Medical evidence dating from 2012 showed that the insured did not have lung disease. His references to a “lung problem” were regarded as self-diagnosed opinions rather than evidence of an established medical condition.
It consequently found that there had been no material non-disclosure concerning either condition.
The Appeal Tribunal upheld the beneficiary’s appeal and set aside the decision issued by the OLTI. It ordered the insurer to pay the policy proceeds, together with interest calculated from the insured’s date of death.
The case demonstrates that identifying information omitted from an insurance application is not, by itself, enough to justify repudiating a policy. The insurer must establish that the information was material to its assessment of the particular risk.
It also shows that the materiality inquiry turns on the medical evidence. A completely treated condition that does not affect longevity and a self-diagnosed complaint unsupported by medical evidence cannot simply be treated as material because they appear in the insured’s medical history.