Medical evidence defeats insurer’s non-disclosure defence
The Appeal Tribunal found that the skin cancer had been completely treated, while evidence showed that the insured did not have lung disease.
The Appeal Tribunal found that the skin cancer had been completely treated, while evidence showed that the insured did not have lung disease.
The NFO upheld the claim rejection and policy cancellation after the policyholder admitted combining damage from two incidents and falsifying the date.
Ubuqhetseba bebhanki yedijithali, amabango omngcwabo angavunywanga, kunye neengxabano zeinshorensi malunga nokungabandakanywa kunye nokugcinwa kwempahla zivele njengezona ndawo ziphambili zoxinzelelo ngo-2025.
Isikhalazo esiphononongwe liZiko leSizwe leeNkonzo zoLamlo lwezeMali (iNational Financial Ombud Scheme) sibonisa indlela ezivavanywa ngayo iimeko ezingabandakanywanga kwi-inshorensi ezinxulumene nezenzo ezingekho mthethweni.
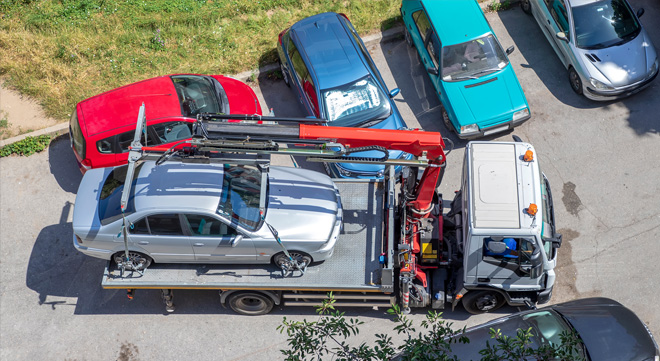
The process differs depending on whether possession is authorised by a court or the consumer agrees to surrender the vehicle voluntarily.
Insurers would have to prove that the life assured knew about and consented to cover taken out at another person’s request.
The doctor’s medical knowledge did not allow Discovery Life to rely on developments he could not reasonably have known about when applying for cover.
A fraud-related cancellation almost 15 years earlier cost the policyholder his tornado claim because he failed to disclose it when applying for cover.
A policyholder’s godfather was recorded as her father despite the adviser knowing the true relationship, leading to a ruling that the insurer must pay the claim.
An NFO case highlights the requirements of Rule 17.8.6 and the consequences when an insurer fails to communicate during a prolonged claims process.
The NFO’s complaints show how SIM requirements, policy schedules, limits, and the circumstances of a theft can affect a claim.
The Appeal Tribunal found that an undisclosed diagnostic test was not material to the insurer’s assessment of the risk and ordered the claim to be paid.
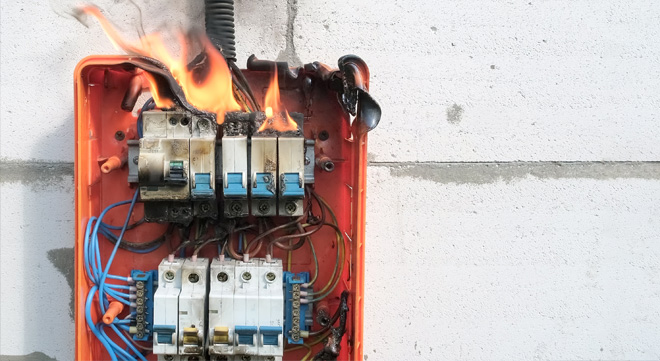
The NFO found that a property owner could not avoid responsibility for an increased risk where poor construction, electrical defects, and tenant conduct contributed to the loss.
Trudie Broekmann Attorneys says South Africa should adopt a mandatory reimbursement framework that goes beyond the UK’s protections for payment scams.
The NFO’s Credit Division recorded a 58% jump in complaints during 2025, while recoveries for consumers more than tripled and favourable outcomes outpaced every other division.
The NFO’s case studies show how disputes over evidence, process failures, and consumer rights can escalate into costly battles between credit providers and customers.
The Appeal Tribunal found that voluntary pre-claim benefit increases were distinct from post-claim escalation and could not be used to support a fixed 10% increase.