Sanlam expects its proposed R21-billion buyout of Santam’s minority shareholders to boost earnings and improve returns, while giving the group more flexibility in how it allocates capital across its South African businesses.
At its Capital Markets Day on 15 October, management outlined how full ownership of Santam could help Sanlam meet its 2030 targets, including its ambition to achieve an adjusted return on equity of more than 20%. The group said the deal would support these ambitions without changing its existing targets.
Sanlam announced the proposed buyout on 5 October, offering R505 a share for the 37.3% of Santam it does not already own. The deal would bring the short-term insurer fully into the group and lead to its delisting from the JSE, A2X and the Namibian Securities Exchange.
Read: Sanlam offers R505 a share to take Santam private
The deal is not yet done. Santam shareholders are expected to vote on the proposal at a general meeting on or around 30 November 2026. The combined offer circular, which will set out the full terms and confirm the meeting details, is expected to be distributed on or about 3 November.
Santam’s independent board has unanimously supported the proposed scheme and said it will recommend that shareholders vote in favour.
The financial case for full ownership
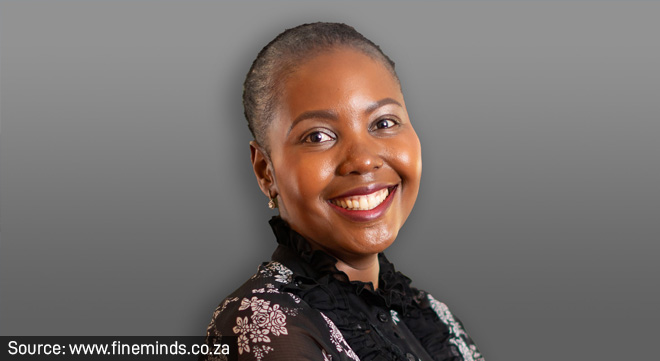
Sanlam chief financial officer Abigail Mukhuba (pictured) said the additional earnings from the deal, funded through borrowing, were expected to lift the group’s return on equity. The benefit would moderate over time as Sanlam paid down the debt.
“The additional earnings financed through leverage lead to ROE accretion, with the benefits expected to moderate as we subsequently deleverage,” she said.
Mukhuba also expects full ownership of Santam to diversify Sanlam’s earnings and create opportunities to grow revenue across its South African businesses.
The deal is expected to support Sanlam’s targets for core earnings growth, adjusted return on equity, adjusted return on group equity value (RoGEV) and dividend growth. The group’s solvency position and sustainability index are expected to remain intact, and its existing financial targets are unchanged.
Those targets include:
- Core earnings and operating profit growth: more than South African consumer price inflation plus six percentage points.
- Adjusted return on equity: above 20%.
- Adjusted return on group equity value: above the risk-free rate plus four percentage points.
- Group economic solvency: between 150% and 190%.
- Dividend growth: above South African inflation plus four percentage points.
- Sustainability index: four out of five.
Sanlam reported an adjusted return on equity of 18% in 2025. The acquisition is expected to contribute to the group’s progress towards its 2030 ambition, but the anticipated benefits have not yet been realised.
Simplifying the group and improving capital allocation
Group chief executive Paul Hanratty described the proposed buyout as the final step in Sanlam’s long-term plan to simplify its South African structure.
“The recent announcement that we wish to acquire the remaining outstanding equity in Santam is really, as I said, the last term of our long-term plan to simplify the structure in South Africa,” he said.
Full ownership would reduce the number of entry points into the group, giving Sanlam greater flexibility over how it allocates capital and helping it make better use of opportunities across its South African businesses, Hanratty said.
The deal could also unlock the final layer of cost synergies between the businesses, while creating opportunities for cross-selling and improving operational efficiency. Hanratty said bringing Santam fully into the group would support Sanlam’s “fortress strategy” in South Africa, with the potential to boost earnings, increase scale and diversify income over time.
He described the acquisition as an important part of Sanlam’s plans to deliver shareholder returns over the next five years.
No major acquisition programme planned beyond Santam
Sanlam’s 2030 ambitions do not depend on a series of further acquisitions. Chief financial officer Abigail Mukhuba said the group had no material capital earmarked for acquisitions through to 2030 beyond bringing Santam fully in-house.
The focus is on growing the businesses Sanlam already owns, improving returns and generating cash. Any future deal would have to meet the group’s strategic and return requirements and compete with the opportunities available within its existing businesses.
The Santam deal is part of a broader shift from restructuring towards getting more out of Sanlam’s established operations.
Mukhuba also expects the transaction to support the group’s dividend ambitions. Sanlam is targeting dividend growth above inflation plus four percentage points, and expects the anticipated improvements in earnings and return on equity to contribute to its longer-term earnings, returns and dividend targets.
S&P expects limited impact on Santam’s credit profile
Three days after Sanlam announced its proposed R21-billion buyout of Santam’s minority shareholders on 5 October, S&P Global Ratings published a report affirming the ratings of Santam and its subsidiaries.
In its report, dated 8 October, S&P said it did not expect the transaction to materially affect Santam’s standalone credit profile. However, it changed its assessment of Santam’s importance within the Sanlam group from “strategically important” to “core”.
The change reflects S&P’s view that Santam would become more integral to the group under full ownership, signalling a stronger strategic commitment from Sanlam. It is not a credit-rating upgrade: S&P affirmed Santam’s existing ratings.
S&P affirmed Santam Ltd’s ‘zaAAA’ national-scale rating, along with the ‘zaAAA’ ratings of Centriq Insurance Company and Santam Structured Insurance. It also affirmed the ‘zaAA-’ ratings on Santam’s outstanding debt instruments.
The report also confirmed ratings for several other entities in the group. These include ‘BB’ ratings for Santam Structured Reinsurance Ltd PCC and Santam Structured Insurance Ltd, both with positive outlooks; a ‘BB-’ rating for Santam Structured Insurance Ltd PCC, also with a positive outlook; and a ‘B’ rating for Santam SI Investments Mauritius, with a positive outlook.
S&P said Santam’s ratings continue to be supported by its strong position in South African property and casualty insurance, diversified product offering, geographic reach, and capital and earnings.
The agency said it would monitor Santam’s capital management and dividend strategy following any move to full ownership.
The transaction remains subject to shareholder approval and other conditions, but Hanratty believes it will strengthen both businesses.
“We believe this step is consistent with our strategy and it improves the prospects both for Sanlam and for Santam,” he said.