The Office of the Pension Funds Adjudicator (OPFA) received a record 13 041 complaints in 2025/26, a 26% increase on the previous year, amid the continuing impact of the two-pot retirement system, greater awareness of the office, and economic pressure on retirement fund members.
Complaints concerning employers’ failure to pay retirement fund contributions accounted for 61.48% of complaints investigated and closed, up from 44.34% in 2024/25. Although the OPFA finalised more complaints than before, its year-end caseload increased, including a substantial rise in unresolved matters older than six months.
The latest intake exceeded the previous record of 11 399 complaints, set in 2018/19, and was 39% above the 10-year annual average of 9 411.
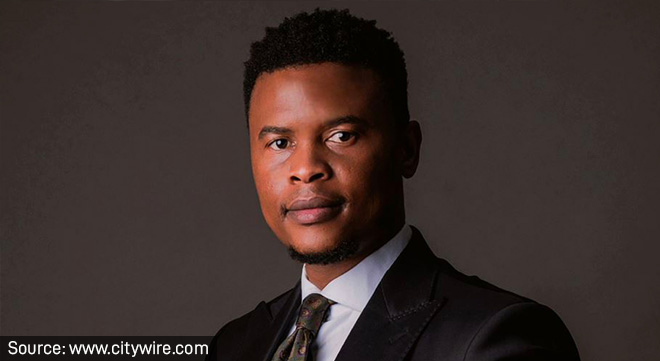
Pension Funds Adjudicator Lebogang Mogashoa (pictured) said the increase was driven mainly by the continued impact of the two-pot retirement system, the office’s enhanced stakeholder-management initiatives, and weak economic conditions. These factors had increased reliance on the OPFA as an accessible forum for resolving retirement fund disputes and highlighted persistent problems in the sector.
The implementation of the two-pot system brought systemic concerns into sharper focus, including inaccurate member records, delays in paying benefits, administrative shortcomings, and employers’ failure to pay contributions.
Unpaid contributions account for a growing share of complaints
Non-compliance with section 13A of the Pension Funds Act, principally employers’ failure to pay contributions to retirement funds, remained the largest category of complaints investigated and closed.
Its share increased by more than 17 percentage points, from 44.34% in 2024/25 to 61.48% in 2025/26. Withdrawal-benefit complaints’ share fell from 38.79% to 22.93%. Together, the two categories accounted for 84.41% of complaints investigated and closed, compared with 83.13% in the previous year.
The categories frequently overlap because members may discover that their employers failed to pay contributions only when they leave employment or try to withdraw a benefit.
Mogashoa said the failure to remit deducted contributions remained a material concern because it directly affected members’ retirement savings and associated risk benefits. These include death, disability, and funeral benefits that depend on the timely payment of premiums to third parties.
The problem was already evident during the first seven months of the two-pot system. Between September 2024 and March 2025, the OPFA received 239 related complaints and 2 246 enquiries. Its 2024/25 report said some members could not access their savings components because employers had not paid contributions, while other complaints concerned delays in processing withdrawals.
The office separately recorded 401 two-pot-related telephone enquiries during 2025/26, with questions about payment status and withdrawal procedures the most common.
The latest report warns that complaints may arise from members seeking access to their retirement components before retirement, which current legislation prohibits. It says National Treasury has indicated that phase 2 of the two-pot system may explore conditional access for retrenched members without another source of income.
Private security fund involved in nearly half of complaints
Complaints involving the Private Security Sector Provident Fund (PSSPF) numbered 6 453, accounting for 49% of all complaints received by the OPFA in 2025/26.
The previous report used a different classification, recording 3 433 complaints lodged by members and 395 lodged by the fund against non-compliant employers. The figures are therefore not directly comparable with the latest total.
In 2024/25, the OPFA said the fund did not appear to have an adequate monitoring system for detecting employers’ non-payment of contributions and had consistently failed to act against defaulting employers. According to the report, millions of rand in contributions consequently became prescribed to the detriment of members.
The office also identified communication breakdowns between the fund and its administrator, Salt Employee Benefits. These included cases in which the fund provided letters of compliance for employers the administrator regarded as being in default. Several such matters were referred to the Financial Sector Conduct Authority.
In 2025/26, problems associated with the fund included inaccurate member information, inadequate monitoring of delinquent employers, and the late or non-payment of retirement and withdrawal benefits.
The concentration was also evident in cases where relief was granted. The PSSPF accounted for 75.60% of the cases involving the 20 funds against which relief was granted most frequently.
It was followed by the Contract Cleaning National Provident Fund at 3.78%, the Transport Sector Retirement Fund at 3.23%, the Alexander Forbes Retirement Fund (Provident Section) at 2.66%, and the Sanlam Umbrella Provident Fund at 1.94%.
Service failures remain prevalent
Service-related complaints accounted for 63.1% of complaints received in 2025/26, up from 48.94% in the previous year.
Together, complaints relating to service, claims and disbursements, and information provided represented 95.28% of the year’s intake. The OPFA attributed these concerns to deficiencies in communication, responsiveness, and administrative effectiveness, particularly in matters involving contributions and benefits.
The office said these failures were, to a considerable extent, preventable through better governance, proactive engagement with members, and timely communication.
One mechanism intended to encourage early resolution is the refer-to-fund process. If a complainant has not first raised the dispute with the fund or employer, the OPFA serves the complaint on the relevant parties and requests a response. Its Early Resolution Unit then assesses the response and either closes the matter as resolved by the fund or allocates it to a case-management team for formal investigation.
The latest report says continued use of the process gives funds an opportunity to engage with members and resolve disputes before they escalate into formal complaints. The office revised its case-management processes to include referring complaints to funds before adjudication.
The report also criticises funds that exceed the prescribed 30-day period for responding to the OPFA. Repeated reminders in mostly straightforward cases place additional strain on the office’s capacity. Mogashoa called for the timely submission of information and effective participation by industry parties in the adjudication process.
Record output and monetary orders
The OPFA finalised a record 11 047 complaints, compared with 10 100 in 2024/25. It issued 6 372 formal determinations, about 17% more than the previous year’s 5 434.
The report records orders sounding in money totalling R99 761 817 during 2025/26.
Of the 9 389 complaints investigated and finalised under the office’s operational-performance measure, 8 552, or 91%, were finalised within 180 days. This exceeded the annual target of 90%, although it was below the 93% achieved in 2024/25.
Mogashoa said sustained demand was placing pressure on operational capacity and underscored the need for process optimisation, stronger case-management disciplines, and faster digital enablement.
The OPFA received 13 041 complaints and finalised 11 047 during the year, a difference of 1 994.
Its unresolved year-end caseload also increased. Matters younger than six months rose from 2 454 to 4 109, while those older than six months increased from 76 to 342.
The OPFA is seeking to move from a predominantly reactive model towards a more proactive and insight-driven institution. Its modernisation plans include cloud-based infrastructure, data and analytics capabilities, streamlined complaint-handling technology, business-process reviews, and resource optimisation.
More determinations challenged at the Tribunal
The Financial Services Tribunal received 104 applications for reconsideration of OPFA determinations in 2025/26, up from 87 in the previous year.
Of the latest applications, 63 were dismissed, thereby upholding the OPFA’s decisions. The Tribunal remitted 25 matters to the office for reconsideration, comprising 17 matters based on the same facts and eight based on new facts.
The annual totals do not necessarily mean that every application received during 2025/26 was decided in the same year.
In 2024/25, the Tribunal issued 83 decisions from 87 reconsideration applications. The annual report records that 56 OPFA decisions were upheld and 27 matters were remitted for reconsideration.
Rising demand meets a membership-based levy model
Levy revenue fell from R120.5 million in 2024/25 to R115.4m in 2025/26. The latest amount was about R3m below the budgeted R118.4m, with the report attributing the shortfall mainly to lower pension fund membership.
The levy is calculated according to the number of eligible pension fund members and the approved rate. The report says this membership base has declined over the longer term while demand for the office’s services has grown, increasing the importance of aligning staffing, systems, funding, and service-delivery capacity with the workload.
Mogashoa said levy-based funding supported the institution’s independence, although uncertainty about levy-approval processes required prudent financial management and continued engagement with relevant stakeholders.
Measures identified in the report include a more efficient levy-approval process, a continuity mechanism when approvals are not finalised by the start of the financial year, adequate reserves to manage timing gaps, and possible special levies in exceptional circumstances such as complaint surges or changes to the office’s mandate.
Mogashoa said the OPFA’s role extended beyond resolving individual disputes to strengthening governance, reinforcing accountability, and maintaining confidence in the retirement funds system.