Insurers should be required to obtain proof that the life assured gave informed consent before a policy is issued on their life at another person’s request, according to the National Financial Ombud Scheme (NFO).
The NFO has called on the Financial Sector Conduct Authority to consider introducing conduct standards or other regulatory requirements that would make proof of informed consent mandatory before such a policy is issued.
The proposal comes amid cases detected by life insurers in which beneficiaries are suspected of arranging or participating in the deaths of insured people to obtain policy proceeds.
According to the Association for Savings and Investment South Africa (ASISA), its member life insurers detected 38 murder-for-money cases in 2024, up from 14 in 2023. Of the 2024 cases, 36 involved funeral policies and two involved life policies.
The 38 cases formed part of 5 505 fraudulent and dishonest life insurance claims detected by ASISA members in 2024.
The NFO said in a statement on 21 September 2026 that requiring informed consent would ensure that people knew that insurance cover had been taken out on their lives, who had taken out the policy, and the extent of the cover.
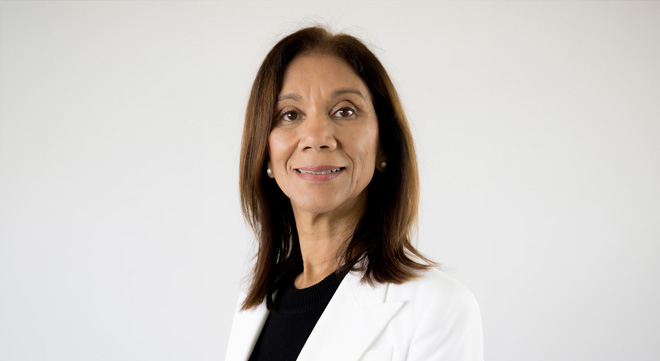
Denise Gabriels (pictured), lead ombud of the NFO’s Life Insurance Division, said many insurers had processes to confirm insurable interest and prevent fraud, but industry practices were not always uniform.
“A mandatory consent requirement would enhance transparency, strengthen consumer protection, reduce opportunities for fraud and abuse, and assist insurers in verifying the legitimacy of policies at inception,” Gabriels said.
The NFO believed a consistent regulatory framework would improve standards across the industry and promote better outcomes for consumers, she said.
It has proposed that the FSCA consult industry stakeholders about introducing the requirement.
When a beneficiary is under suspicion
The NFO has also set out its approach to complaints involving claims where a beneficiary is suspected of playing a role in the death of the life assured.
Gabriels said the NFO would generally refrain from ruling in favour of a beneficiary who had not been cleared of suspicion while a South African Police Service investigation or criminal proceedings remained under way.
In these circumstances, the NFO would ordinarily advise the beneficiary that its complaint process should await the outcome of the criminal matter.
The beneficiary could return to the NFO after a court had delivered a verdict, charges had been withdrawn, the National Prosecuting Authority had decided not to prosecute and issued a certificate of nolle prosequi, or the matter had otherwise been finalised.
According to the NFO, this approach is intended to protect the integrity of the criminal justice system and the complaint-resolution process by avoiding inconsistent outcomes. It also allows allegations of serious criminal conduct to be investigated by the relevant authorities.
South African law recognises the public-policy principle that a person should not be allowed to benefit from his or her own unlawful conduct. The NFO said this meant someone who intentionally caused another person’s death should not be permitted to benefit from that death through an inheritance or insurance proceeds.
However, the NFO emphasised that an allegation did not constitute proof of wrongdoing.
It said complaints had to be resolved consistently with the law, public policy, the principles of natural justice, and fairness to the parties involved.
When an investigation drags on
The NFO’s general practice of awaiting the outcome of the criminal process is not absolute.
Gabriels said criminal investigations and prosecutions could take years to conclude. In some matters, investigations remained unresolved for extended periods through no fault of the claimant.
“It would be unjust for insurers and beneficiaries to remain in a state of uncertainty indefinitely while awaiting the outcome of a criminal investigation that shows little progress,” she said.
Where there had been an unreasonable delay in finalising the criminal matter, the NFO could require the insurer to assess the claim on its merits, based on the available evidence and the policy’s terms and conditions.
The NFO also states that an insurer may be required to assess a claim on its merits where the police have confirmed that the beneficiary is not a suspect.
“This approach recognises that while public policy requires vigilance against fraudulent and unlawful claims, indefinite delays may also undermine the rights of innocent policyholders and beneficiaries,” Gabriels said.
Where there had been an unreasonable delay, the claim would still have to be assessed on its merits, based on the available evidence and the policy’s terms and conditions.
The proposed informed-consent requirement concerns safeguards before a policy is issued, whereas the NFO’s approach to pending criminal proceedings concerns how it handles complaints where a beneficiary remains under suspicion.
Each matter would nevertheless be considered on its own facts, taking into account the available evidence, the status of the criminal investigation, the interests of other affected parties, and fairness.