
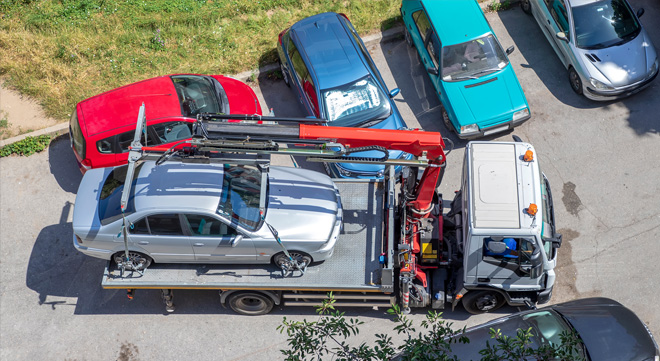

Falling behind on vehicle repayments may place a consumer in default under the finance agreement, but the credit provider must still follow the appropriate process to obtain possession of the vehicle.
A credit provider may ordinarily obtain possession through legal enforcement or with the consumer’s consent. Legal enforcement generally requires a court order authorising the vehicle’s return. Voluntary surrender, by contrast, is initiated by the consumer under section 127 of the National Credit Act (NCA).
Nerosha Maseti, Lead Ombud of the Banking and Credit Division of the National Financial Ombud Scheme (NFO), said consumers should understand which process is being followed before handing over the vehicle or its keys, or signing any document.
Repossession and voluntary surrender are different processes
Where a consumer is in default and the credit provider wants to repossess and sell the vehicle without the consumer’s consent, it must ordinarily follow the enforcement process prescribed by sections 129 and 130 of the NCA, Maseti said.
This process generally begins with a section 129 notice, which alerts the consumer to the default and the options available to address it before legal proceedings are instituted.
Subject to the requirements in sections 129 and 130, the credit provider may institute court proceedings after the applicable period has elapsed. If a court grants judgment ordering the vehicle’s return, the credit provider may obtain a warrant authorising the Sheriff of the Court to take possession of it.
Voluntary surrender under section 127 follows a different process. It is initiated by the consumer giving the credit provider written notice terminating the agreement and returning the vehicle as prescribed.
Because voluntary surrender occurs with the consumer’s consent, the credit provider does not need a court order. Maseti said surrender may avoid the additional legal costs associated with court proceedings. However, any financial benefit will depend on the vehicle’s eventual sale and the amount still owing.
Check the collector’s identity and authority
A consumer should not assume that someone has lawful authority to take the vehicle merely because the person claims to represent the credit provider.
Where possession is being obtained under a court order, the process is ordinarily carried out by the Sheriff under the authority of a warrant. Where the consumer has chosen to surrender the vehicle, collection may be arranged through the credit provider or its authorised representative.
Before handing over the vehicle or its keys, the consumer should establish the person’s identity, whom the person represents, and the basis on which possession is being sought.
Maseti said a consumer who is approached should request official identification. If the person relies on court proceedings, the consumer should ask to see the relevant court order and warrant. The consumer should also contact the credit provider directly, using known contact details, to verify the circumstances.
If the approach feels unsafe, the consumer should leave the scene. Where appropriate, arrangements may be made for the vehicle to be delivered at a suitable location, such as the Sheriff’s office or the credit provider’s premises.
This is not advice to obstruct the Sheriff from executing a valid warrant. A consumer who disputes a court order, warrant, or its application may require urgent independent legal assistance.
Understand what you are being asked to sign
A consumer is not obliged to surrender a vehicle merely because a representative of the credit provider asks for it, particularly if no court order compelling delivery has been produced.
Maseti said the decision whether to surrender the vehicle voluntarily remains the consumer’s.
Handing over a vehicle, consenting to its collection, and terminating the credit agreement are not necessarily the same thing. The effect of a voluntary-surrender, consent, or collection document depends on its terms and the circumstances in which it is signed.
Before signing, the consumer should establish whether the document:
- merely records the vehicle’s collection;
- gives consent to the credit provider taking possession;
- amounts to voluntary surrender;
- terminates the credit agreement; and
- authorises the vehicle to be valued and sold.
The consumer should also understand the costs that may be deducted, the possibility of a remaining shortfall, the process that will follow, and the rights available under the NCA.
Maseti said a consumer who signs will generally be bound by the document’s terms, subject to any legal right to challenge its validity or enforceability. Anyone who is uncertain about the implications may decline to surrender the vehicle and obtain independent legal advice before signing.
Returning the vehicle may not settle the debt
Within 10 business days after receiving the consumer’s termination notice or the returned vehicle, whichever occurs later, the credit provider must give the consumer written notice setting out the vehicle’s estimated value and other prescribed information.
Section 127 gives the consumer 10 business days after receiving this valuation notice in which to withdraw the termination notice unconditionally and resume possession of the vehicle, unless the consumer is in default under the credit agreement.
Maseti clarified that, in the NFO’s view, a consumer who is in default may remedy the default to exercise this option.
She said valuation notices typically confirm that consumers may withdraw their termination notices and resume possession if they pay all outstanding amounts due, including agreed costs, under the credit agreement or an applicable judgment.
Consumers should not assume that paying one missed instalment or only part of the arrears will be sufficient. They should contact the credit provider promptly to establish the amount that must be paid and the arrangements for resuming possession.
If the termination notice is not withdrawn, the vehicle is sold and the net proceeds are applied to the finance account. If the proceeds are insufficient, the consumer may remain liable for the shortfall. A surplus must generally be paid to the consumer.
The credit provider must account for the sale
If a voluntary surrender proceeds, the credit provider must sell the vehicle as soon as reasonably practicable for the best price reasonably obtainable.
This does not guarantee a particular retail or market price. It does, however, provide a standard against which the handling of the sale can be assessed.
After the sale, the credit provider must give the consumer a written statement setting out:
- the settlement value immediately before the sale;
- the gross amount realised;
- the net proceeds after permitted default charges, if applicable, and reasonable sale costs have been deducted; and
- the amount credited or debited to the consumer’s account.
The statement should show how the proceeds were applied and how any shortfall or surplus was calculated. Where the net proceeds are less than the settlement value, section 127 permits the credit provider to demand payment of the remaining shortfall when it issues the statement.
Consumers should compare the estimated valuation with the selling price and examine the settlement value, gross proceeds, deductions, net proceeds, and final balance.
A difference between the estimated value and the sale price does not by itself show that the credit provider failed to obtain the best price reasonably available. However, a substantial unexplained difference, unclear deductions, or the absence of the required statement may warrant further enquiries.
Request the documents if something appears irregular
A consumer who believes the vehicle was taken without proper authority, the correct process was not followed, or the sale was improperly handled should first raise the dispute with the credit provider in writing.
Maseti said the consumer should request:
- relevant notices and proof of delivery;
- any summons, judgment, court order, or warrant relied on;
- any signed voluntary-surrender or consent document;
- records relating to the vehicle’s valuation and sale; and
- a detailed calculation showing how the proceeds were applied and whether a shortfall or surplus remains.
Two complaints described by the NFO illustrate why proof of the process matters, although their outcomes depended on their particular facts.
In the first case, a minibus taxi that had been impounded was released to the financing bank instead of being returned to the consumer. The NFO found that the consumer had breached the finance agreement by allowing the vehicle to cross the border without complying with its requirements. However, it also found that the bank had not followed the proper legal process when it retained the vehicle.
The bank accepted the NFO’s recommendation to pay the consumer R30 000 for distress and inconvenience and write off the legal and storage costs charged to her account.
In the second case, the consumer was substantially in arrears and had made limited repayments while having the use of the vehicle. However, the bank could not provide a signed voluntary-surrender document or evidence of judicial authority for taking it.
After considering the circumstances, the NFO recommended that the bank write off the shortfall of about R300 000. The bank accepted the recommendation.
According to the NFO, the complaints show that a consumer’s breach or default does not allow a credit provider to dispense with the required process or proof of its authority. The remedies were based on the facts of the individual complaints and will not necessarily follow whenever an irregularity occurs.
Where consumers can obtain assistance
If the credit provider does not resolve the complaint, the consumer may be able to approach the NFO.
Maseti said the scheme can consider complaints that a bank or credit provider repossessed, retained, or sold a vehicle without following the appropriate process, as well as disputes about the fairness of the institution’s conduct.
The NFO provides free, independent, and impartial dispute-resolution services. Its jurisdiction will depend on the financial institution and complaint concerned.
Broader concerns about compliance with the NCA may be referred to the National Credit Regulator, which has statutory enforcement powers.
Where a dispute concerning the sale of a surrendered vehicle cannot be resolved, section 128 provides a mechanism under which the consumer may, in the circumstances set out in the NCA, apply to the National Consumer Tribunal to review the sale.
Independent legal assistance should be sought urgently if court proceedings have commenced, a court order is being challenged, there is an immediate dispute about possession, or urgent court intervention is required.


