
Car repossession: what the bank must do and what you should check
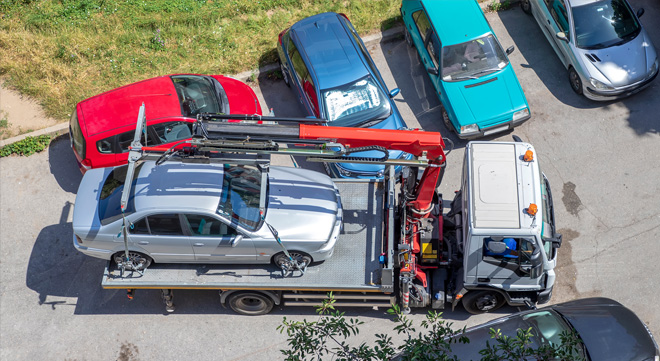
The process differs depending on whether possession is authorised by a court or the consumer agrees to surrender the vehicle voluntarily.
The process differs depending on whether possession is authorised by a court or the consumer agrees to surrender the vehicle voluntarily.
The Adjudicator upheld a fund’s reliance on affordability requirements but cautioned it about poor service delivery and delayed communication.
The High Court recognised the potentially serious prejudice to the applicant but found that his evidence did not meet the threshold for interim relief.
The NFO’s case studies show how disputes over evidence, process failures, and consumer rights can escalate into costly battles between credit providers and customers.

The NFO’s 2025 annual report offers a glimpse into the disputes that reach the banking ombud – and the lessons they hold.
The SCA rules that section 127(8) of the NCA empowers Magistrates’ Courts to hear these claims, but it does not bar High Court proceedings.
Lenders and dealers should dig deeper into living costs, dependants, and insurance obligations to avoid stretching consumers beyond their means.
Attend this practical session on PCC 23A, Directive 11, and the steps needed to submit a complete and defensible return.
A High Court ruling has refused FirstRand’s summary judgment bid, signalling stricter scrutiny of debt claims, documentation, and enforcement processes.
The Credit Association of South Africa sets out key aspects of the process that consumers should understand.
The NFO says consumers can limit costs by acting early through voluntary termination, private sale, or Sell Assist programmes.
The High Court rejects arguments that excess transactions processed during a system error amounted to unlawful credit extension.
MBSE visits automotive dealerships to equip F&I professionals with CPD, FICA, and POPIA training tailored for their workplace needs.
The National Debt Counselling Association is pushing for a regulated mechanism to remove consumers from incomplete debt counselling caused by life-changing events.
The SCA rules that buyers may rely on actio redhibitoria to unwind financed vehicle purchases marred by latent defects, even when the deal falls under the NCA.
A subsequent, corrected section 129 notice cannot cure defects in the original notice once summary judgment proceedings have begun.
INkundla ithi ababoneleli ngetyala kufuneka baqinisekise ukungafihli ngokupheleleyo ekuvezeni uhlobo, iindleko, kunye neziphumo zenkxaso-mali yeze ntlawulo.


