An insurer could not justify reconstructing a doctor’s disability policy by characterising his use of orthotics as treatment for a chronic pain disorder, the National Financial Ombud Scheme (NFO) found.
The NFO ruled that Discovery Life had failed to prove material non-disclosure when the doctor applied for the policy. It said the evidence did not support the insurer’s description of his condition and treatment as “chronic pain” requiring “constant pain management”. The case was included in the NFO’s 2025 annual report.
The complainant, a medical doctor who worked in a hospital, applied for the policy with Discovery Life in January 2021. When he lodged a disability claim in 2023, the insurer invoked material non-disclosure.
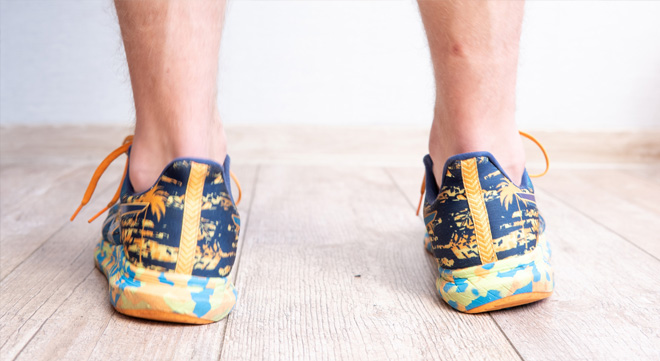
According to the insurer, the complainant had failed to disclose that he had consulted a podiatrist for overpronation since the age of 17 and wore orthotics in his shoes to address the condition.
The insurer maintained that this amounted to a chronic pain condition requiring constant pain management, which the complainant should have disclosed when applying for the policy.
It also relied on the fact that the complainant had been diagnosed with plantar fasciitis in 2017 and had required a night splint.
An insurer relying on material non-disclosure bears the onus of proving that relevant information was not disclosed and that the non-disclosure was material.
After considering the evidence and the parties’ arguments, the NFO issued a provisional ruling finding that Discovery Life had failed to discharge this onus.
Insurer points to complainant’s medical knowledge
The insurer rejected the provisional ruling. It argued that the complainant’s work as a medical doctor meant he had particular knowledge of the symptoms he was experiencing when he applied for the policy and their potential consequences.
According to the insurer, those consequences had subsequently manifested, demonstrating the risk associated with the condition and reinforcing the significance of the information at the application stage.
The NFO found, however, that the insurer could not rely on information that emerged at the claims stage, or at any other time after the policy began, if the complainant had not known and could not reasonably have known that information when he applied for cover.
As the NFO put it: “You cannot disclose what you do not know.”
The NFO also found that the insurer appeared to have applied a subjective test by placing particular emphasis on the complainant’s medical profession. The test for material non-disclosure was objective.
It considered it inappropriate and unreasonable to describe the use and periodic replacement of orthotics for pronation as chronic pain and constant pain management.
The seriousness of the complainant’s condition and treatment had to be determined from the evidence, the NFO said, rather than from terminology that overstated their severity.
Application question considered
The insurer relied on the complainant’s negative answers to several questions asked when he applied for the policy. These included: “Have you ever been diagnosed or treated for fibromyalgia … or any chronic pain disorders?”
The NFO found that the question, as formulated, would not have prompted a reasonable person to disclose foot pain caused by pronation or the use of orthotics to manage it.
The question referred to conditions of a more serious nature, such as fibromyalgia. The NFO found that foot pronation treated with orthotics did not fall into this category.
It issued a final ruling that Discovery Life had failed to prove material non-disclosure at the application stage.
The insurer abided by the ruling. After assessing the disability claim under the policy’s original terms, it paid the claim.
The case illustrates that material non-disclosure must be assessed according to what an applicant knew, or could reasonably have known, when applying for cover. An insurer cannot use later developments to inflate the apparent seriousness of an earlier condition or treatment.