What are clients really looking for when they choose a financial adviser?
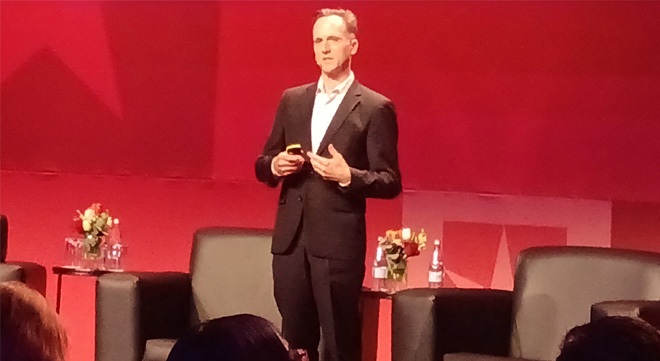
It was the question Dr Ryan Murphy (pictured), Morningstar’s global head of behavioural insights, put to delegates at the Morningstar Investment Conference South Africa in Cape Town on 10 September 2026.
It is also the question behind a Morningstar study published in February 2026, The Evolving Value of Advice: What Clients Look for When They Hire a Financial Advisor.
Murphy said existing research and industry commentary often focus on specific reasons for seeking advice, such as retirement planning, receiving a windfall, increased income, or tax questions.
Those are valid reasons. But they do not capture everything advisers do for clients, he said.
One example is behavioural coaching. Murphy referred to earlier research from Merrill Lynch and Vanguard showing the different ways advisers create value, including the contribution of behavioural coaching.
Yet in earlier Morningstar research, when investors were asked to rank the different things they valued from an adviser, behavioural coaching came at the bottom of the list.
“Behavioural coaching is a tough sell,” Murphy said.
The Morningstar study asked clients themselves.
What clients actually said
The study drew on responses from 623 clients in the United States who had chosen and were paying for a financial adviser. They were asked to list, in their own words, some of the reasons why they had hired their adviser.
The two most common reasons were tied at 32%: discomfort handling financial issues and having a specific financial need.
Clients who fell into the first category said things such as, “I don’t like making financial decisions” and “I don’t know enough to make the best decisions”.
The second category covered the more familiar reasons for seeking advice: tax planning, investing, income management, retirement planning, and annuities.
Behavioural coaching was the third-largest category, at 17%.
Here, the responses included: “I lack discipline to stay invested when the market is erratic” and wanting “a sane voice” to bounce ideas off. Other responses referred to getting help navigating financial choices and gaining confidence in their financial security.
The other reasons in the top five were recommendations from friends or family, at 12%, and the quality of the relationship with the adviser, at 10%.
Across the responses, Morningstar classified 60% of the motivations as emotional and 40% as financial. Four of the five largest categories fell on the emotional side. The categories can overlap, so these figures should not be read as separate groups that add up to 100%.
Nobody called it behavioural coaching
Clients did not use the term “behavioural coaching”.
“That was a surprise, and it’s not that people aren’t interested in this stuff. This is mentioned a lot,” Murphy said. “They just never use the phrase behavioural coaching.”
Murphy said “behavioural coaching” is a term familiar to people in the industry, but not to investors.
“For those of us in that field, we know exactly what that means, and we banter this term around,” he said. “But when it comes to investors, how they think about it, what they’re looking for, they don’t use the phrase behavioural coaching.”
The research defines behavioural coaching broadly. It includes helping clients understand their financial plan, motivating them to stick to it, and providing guidance about what to do – and what not to do – in particular financial situations.
The clients described the underlying need in everyday terms: staying invested when markets are erratic, having someone to discuss decisions with, understanding what they were doing and feeling more confident about their finances.
Start with the goal
Murphy’s answer was to rethink how these different sources of value are described to clients. He kept coming back to the reason people invest in the first place.
“People become investors to reach their financial goals,” he said.
Investing requires patience and delaying gratification, while also putting money into markets where the outcome is uncertain.
“So why would anyone do these two things? Goals.”
The more the investment process can be framed around achieving financial goals, Murphy argued, the more naturally it connects the investment process with the behaviours required to get there.
He used “stay on track” as an example of language that can describe behavioural support without labelling the client’s emotions. An adviser can help clients to understand their financial plan, stay on track, and navigate financial decisions, while also addressing some of the discomfort identified in the research.
Murphy contrasted this with a hypothetical adviser value proposition built around professional financial advice, 20 years of experience, retirement planning, tax management, and wealth accumulation.
“It’s not bad. It’s not wrong. It’s just evidently forgettable. It doesn’t reach people,” he said.
The alternative was to put the client’s financial goals at the centre, while describing the education, guidance, and support provided along the way. Murphy said there is no single formula for doing this, but the research provides a way to think about whether an adviser’s value proposition reflects the reasons clients actually seek advice.
The language matters
The Morningstar research found that some of the emotional motivations for seeking advice may remain unspoken. A client may arrive with a specific financial problem without saying that they also lack confidence in making financial decisions or want help staying the course.
The researchers found that how these benefits are described matters. Colloquial language, examples, and references to common experiences can make the underlying value easier for clients to recognise.
For Murphy, that extends beyond the phrase “behavioural coaching”.
“If there’s anything to take from this, is keep it simple,” he said.
Morningstar’s research on trust has also found jargon to be one of the factors that can reduce trust in an adviser.
“Jargon pushes people away,” Murphy said.
His suggestion was to use AI as a test of whether communications are as simple as they could be: give it a paragraph and ask it to explain the content as if to a 12-year-old. The purpose, he said, is not to speak to clients like children, but to expose acronyms, technical terms and unnecessary wording.
“That’s what reaches clients. That’s what clients understand. Jargon doesn’t do it.”