

Introducing an artificial intelligence product into a financial-advice practice can be as easy as buying a licence or opening a free account. Understanding what happens to client information, assessing the product’s output and accepting responsibility when it is wrong are considerably harder.
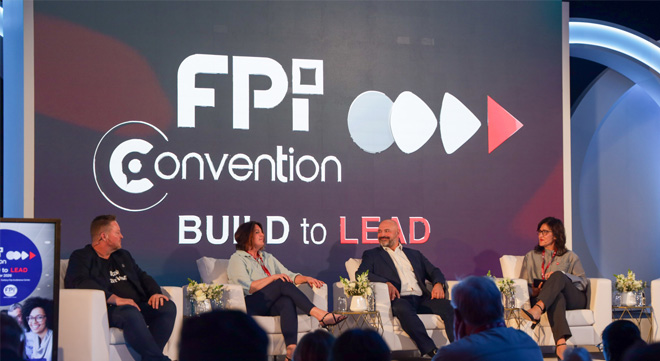
Panellists at the FPI Professionals Convention in Cape Town said responsible AI use requires more than selecting a product and keeping a person involved in the process. Advice practices need governance around how AI products are selected and used, while advisers require sufficient professional knowledge to recognise inaccurate output.
The discussion, on 7 October 2026, followed the release of the Financial Planning Standards Board’s second annual global research into AI’s role in financial planning. As reported separately, the study found that adoption was accelerating while firms’ governance arrangements remained uneven.
The panel was moderated by Lelané Bezuidenhout, a Certified Financial Planner® professional and chief executive of the Financial Planning Institute of Southern Africa. The speakers were Jen Mckay, director of advice-tech consultancy Linktank; Henry van Deventer CFP®, the head of omni-channel advice at Liberty Group; Francois du Toit CFP®, the founder of PROpulsion, a business accelerator, professional community, and media network for financial services providers; and Millie O’Brien, who leads business operations at Marloo, an AI-first platform and assistant designed for financial advisers and wealth managers. O’Brien participated virtually.
Easy adoption can bypass normal scrutiny
Mckay said buying an AI licence or starting to use a free product was considerably easier than establishing the governance required to use it responsibly.
This accessibility could allow products to enter a business without the rigour usually applied to technology procurement. The problem was not necessarily that advisers were careless. Rather, they might begin using a product before considering the governance implications.
Even a seemingly limited application, such as recording a client meeting and generating a transcript, raises questions about what information is sent to the provider and how it is processed.
Mckay noted that client information leaves the meeting when it is sent to a transcription product, even if the resulting notes are never transferred to the practice’s customer relationship management system.
She said practices should decide what information could be entered into an AI product, under which circumstances it could be used and who would be accountable if the product generated an incorrect output.
Mckay also warned that firms were introducing AI into environments where systems and data were not always well integrated. Adding AI would not, by itself, resolve weaknesses or inconsistencies in the information on which the technology relied.
She further cautioned that widely available products may have been developed primarily for markets outside South Africa. Advisers should therefore consider whether outputs reflect the local legal, regulatory, and financial-planning context.
AI cannot supply expertise advisers no longer possess
Keeping a person “in the loop” is frequently presented as protection against AI-generated errors. But human review provides limited protection if the reviewer lacks the knowledge required to recognise that something is wrong.
Bezuidenhout rejected a suggestion that advisers no longer needed strong technical ability because AI could provide the necessary expertise.
Without sufficient technical knowledge, an adviser may be unable to recognise when an AI-generated answer is wrong. Meaningful human review therefore depends on the adviser having the expertise required to identify an incorrect answer.
Van Deventer said advisers needed to ask good, critical questions and evaluate the answers they received. The panel’s wider message was that responsibility for using those answers remained with the professional.
Protecting client information requires more than a paid product
Du Toit focused on the questions practices should ask before placing client information into an AI product.
He distinguished between whether a provider uses information to train an AI model and the broader question of how the provider processes and retains that information.
Opting out of model training may address one concern. It does not, by itself, establish where the data is processed, whether it is retained, how long it remains available, or what contractual terms govern the processing.
Similarly, paying for a product does not automatically settle every privacy question.
A business or enterprise licence may give a practice access to a data-processing agreement and different data-use terms. Du Toit said the distinction between consumer and business licensing was important, but firms still needed to examine the terms applying to the particular product.
He encouraged practices to establish:
- what the provider’s terms and privacy policy say;
- whether a data-processing agreement is available;
- where client information is processed;
- whether the information is retained and for how long; and
- what contractual terms apply to the processing.
These were practical issues raised during the panel rather than a definitive statement of the legal obligations applying to every product and firm.
Du Toit also distinguished disclosure from informed consent. Simply telling a client that the practice uses AI does not necessarily establish that the client understands what will happen to the information.
He cautioned against automatically treating general disclosure and informed consent as equivalent. The panel did not establish when consent is legally required or what would constitute adequate consent in every circumstance.
Will the record still exist when it is needed?
AI also raises questions about the records practices retain.
Du Toit asked whether AI interactions that contributed to an advice outcome or client communication were being retained, where those records were stored and whether they would remain available if the practice needed to reconstruct its process years later.
He referred to his own experience of being unable to retrieve an older conversation from an AI product. This raised the question of how a practice could reconstruct its work if the relevant exchange was no longer available.
The panel did not prescribe what the legal record must contain. Its discussion raised the question of whether firms’ existing record-keeping arrangements adequately cover AI-assisted work.
AI governance cannot be delegated away
Bezuidenhout said key individuals could not leave responsibility for AI governance entirely to an IT department. Those overseeing financial-services businesses needed to understand the AI products being used.
O’Brien acknowledged that procuring and assessing technology was not necessarily a core capability for someone whose principal business was financial advice.
Advisers may need assistance understanding their obligations, identifying suitable guardrails and deciding how a product should fit into their established workflows. She said professional and industry bodies could help advisers to navigate these requirements.
O’Brien also distinguished between generic AI products and applications designed for financial-advice workflows. She argued that industry-specific applications were better positioned to support industry-specific tasks.
O’Brien said technological change was moving too quickly for regulation to prescribe an answer for every development. In her view, professional principles, standards, and guidance therefore had an important role in shaping responsible behaviour.
She argued that firms still needed to make responsible decisions when detailed regulation had not yet addressed a particular application.
Clients are using AI before meeting advisers
The panel also considered how advisers should respond when clients use AI themselves.
Du Toit said younger clients may consult chatbots before approaching a financial planner. He referred to a young person who had felt uncomfortable and out of their depth during an initial meeting with an adviser because the financial concepts being discussed were unfamiliar.
Access to AI could allow clients in that position to explore unfamiliar terminology and financial questions privately before returning to an adviser, he said. They might then enter the conversation with more context and feel better equipped to participate. The important issue was how advisers responded when clients arrived with information obtained from AI.
O’Brien said advisers needed enough AI literacy to ask whether a product cited sources and what logic produced its conclusion. The panel’s broader point was that advisers must be able to assess AI-generated information and place it in the client’s circumstances.
The benefits are difficult to ignore
The panel did not present AI only as a governance problem.
Van Deventer argued that AI’s potential benefits were becoming increasingly difficult for advisers to ignore. He said the technology could support internal business operations and client engagement by helping practices identify clients who needed attention, prepare communications, and simplify complicated information.
Automating selected administrative and process-driven work could allow advisers to devote more time to advice and client conversations.
Van Deventer attributed some resistance to AI adoption to behavioural inertia. Using AI effectively may require professionals to unlearn established ways of working rather than simply add new products to existing processes.
Use AI to make advice more personal
O’Brien invited advisers to consider the most meaningful interaction they had experienced with a client during the preceding year. The adviser’s value often lay in the personal element of significant moments, including investing a first salary or navigating retirement.
Du Toit warned that AI could create an “illusion of empathy”. As AI becomes more convincing in its interactions, he said advisers would need to strengthen their interpersonal skills rather than assume that human connection remained an automatic advantage.
AI may assist with the work surrounding client engagements, but it does not remove the need for an adviser who understands the client’s circumstances and accepts responsibility for the advice.
The opportunity is to use AI to create more time for the professional judgement, explanation, and human engagement that make advice valuable.


