

The shift towards principles-based and outcomes-focused regulation gives regulated organisations and professionals greater discretion over how they meet regulatory objectives. It also makes them more responsible for the decisions they take.
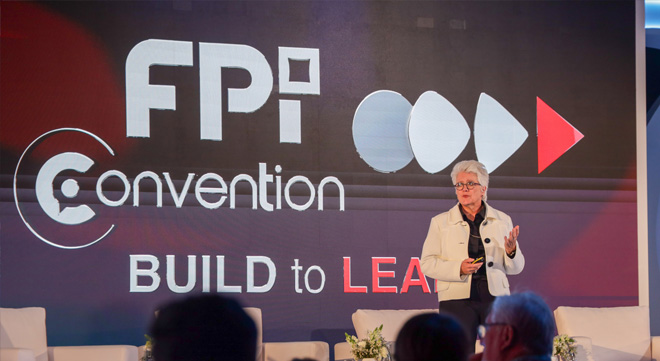
Rianné Potgieter, chief executive of the International Federation of Compliance Associations, told delegates at the FPI Professionals Convention on 7 October 2026 that the financial environment has become too complex for regulators to write a rule covering every possible situation.
Regulators are therefore increasingly setting principles and required outcomes, while leaving organisations to decide how these should be applied in their circumstances.
Professionals must understand the purpose of a requirement, identify the risk it seeks to address, and determine how the intended outcome will be achieved.
Greater discretion therefore brings greater accountability.
Ask what is right, not only what is allowed
Rules-based compliance tends to focus on whether a particular action is permitted or prohibited. Principles-based regulation also requires professionals to consider whether an action supports the purpose of the law and the outcome the regulator wants to achieve.
Potgieter contrasted asking “Is it allowed?” with asking “Is this right?”
An organisation may comply with the literal wording of a requirement without necessarily achieving its intended purpose. Understanding the rule is therefore not enough. The professional must understand the risk it is designed to manage.
This may require decisions to be made without certainty. Referring to suspicious-transaction reporting, Potgieter said a professional cannot wait for conclusive evidence before reporting a suspicion.
Principles-based and risk-based approaches are not the same
Potgieter cautioned against treating principles-based and risk-based regulation as interchangeable concepts.
A principle identifies the objective or standard to be achieved. The risk assessment informs the response required in the circumstances.
She illustrated the distinction by comparing a fixed speed limit with a warning that a driver is approaching a school. The speed limit prescribes a maximum speed. The school warning requires the driver to assess the conditions and respond to the increased risk.
The two approaches therefore work together. The principle indicates what must be achieved, while the assessment of risk shapes the response.
Trust can create compliance blind spots
A trusted client relationship is valuable, but familiarity can make professionals less alert to warning signs.
The closer the relationship, the easier it may become to assume that the client presents little or no risk. Professionals may overlook red flags or avoid difficult questions because they fear offending someone with whom they have spent years building a relationship.
The fees generated by the client can add further pressure, Potgieter said.
A longstanding client should therefore not be exempt from appropriate scrutiny. This is particularly important when the information available may give rise to a reportable suspicion.
The adviser-client relationship may be deeply personal, but it remains a professional relationship whose boundaries must be maintained.
Small exceptions can become ethical drift
Ethical failure does not necessarily begin with a deliberate decision to behave improperly.
Potgieter described a gradual process that may begin with a small exception for a trusted or important client. The professional rationalises the departure, allows the conduct to become more serious and eventually begins to regard it as normal.
By then, the professional may already have crossed an ethical boundary.
The initial decision can appear insignificant, particularly where the client is familiar and trusted. The danger lies in allowing repeated rationalisation to change what the professional considers acceptable.
Professionals must therefore remain alert to minor exceptions and conduct that has become familiar through repetition.
Financial planners must become T-shaped professionals
Sound judgement depends on sufficient knowledge. Potgieter urged financial planners to become “T-shaped” professionals.
The vertical part of the T represents deep knowledge and expertise in financial planning. The horizontal part represents a broader understanding of developments affecting the profession, including artificial intelligence, crypto assets, fintech, and evolving payment systems.
She added that planners should connect these developments with risk and regulation.
Financial planners need enough knowledge to assess how these areas affect their work and recognise when further learning or specialist assistance is required.
Professionals need several forms of intelligence
Technical ability alone is insufficient for professionals operating in a fast-changing, principles-based environment. Potgieter discussed intellectual intelligence, emotional intelligence, adaptability, and moral intelligence.
Intellectual intelligence
Financial planners must maintain deep expertise in their core field while learning about developments that affect their work. This knowledge enables them to interpret requirements, understand emerging issues and connect regulatory principles with the risks involved.
Emotional intelligence
Professionals need self-awareness, the ability to deal appropriately with other people and the confidence to ask difficult questions. They should understand their own biases and recognise when familiarity or fear of causing offence is influencing their response to a client.
Adaptability
AI, fintech, crypto assets, and payment developments are changing how transactions and advice are delivered. Professionals must adapt their knowledge, methods and processes, but Potgieter drew an important boundary: adaptability is useful for methods and processes, not for values. Methods may change as the environment develops, but underlying values should remain stable.
Moral intelligence
Moral intelligence provides the foundation for the other capabilities. A person may be technically capable, emotionally perceptive and highly adaptable, but these abilities can be applied improperly if they are not supported by integrity. Without a stable moral foundation, adaptability may make someone more effective at doing the wrong thing. Moral judgement determines how the other capabilities are used.
Technology removes friction, not accountability
Potgieter said financial services are becoming increasingly “frictionless”.
AI, automation, faster payments, and crypto assets are reducing the time needed to complete transactions. Greater speed also removes some of the pauses during which a person might previously have noticed an anomaly and intervened.
Professionals cannot defend a decision by saying that AI produced the answer. They remain responsible for checking any output on which they rely.
They must also understand what data may be entered into open systems.
Technology may improve efficiency, but accountability remains with the professional.
Principles are written for leaders
Organisations cannot wait for regulators to provide instructions for every possible situation. They must decide how regulatory principles and organisational values will be applied in their own environments.
Potgieter framed this as a leadership responsibility. Rules can be followed, but principles require someone to interpret the objective, assess the risk and decide on the appropriate response.
She described rules as being written for followers and principles as being written for leaders.


