

Clients are increasingly living, working, investing, and doing business in more than one jurisdiction. For advisers, that can create problems around currency, estate duty, beneficiaries, ownership, and compliance. It can also create an opportunity.
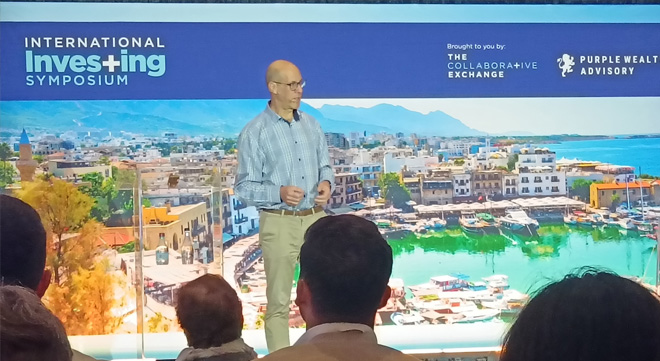
Harry Joffe (pictured), head of legal at Discovery Life International, used the International Investing Symposium in Cape Town on 1 October 2026 to take advisers through some of the situations he encounters – and how they can continue assisting clients when their financial lives move beyond South Africa.
His presentation centred on Discovery’s Dollar Life Plan, an offshore life insurance product issued through Discovery Life International’s Guernsey branch. Premiums and benefits are denominated in US dollars. Clients with offshore funds can pay annual premiums directly from a dollar-denominated bank account, while policy proceeds are paid in dollars only into a foreign bank account – not into a South African bank account. Those living in South Africa can pay premiums from this country using their R2-million Single Discretionary Allowance (SDA).
Joffe described it as: “Proper offshore risk cover.”
The product was the vehicle for the discussion, but Joffe’s message to advisers was broader: look at where the client’s liabilities, beneficiaries, and money are going to be when the policy is needed.
The problem may be the currency
One of Joffe’s first examples involved a South African client with a property in London.
The client needs a UK will, but the bigger planning question is what happens when the property creates a UK tax liability on death of the owner.
The UK inheritance tax rate is 40%, with a £325 000 nil-rate band for 2026/27.
The estate may be largely in South Africa, but the tax bill is in pounds.
“How is a local South African-rand estate going to generate offshore currency to pay the situs tax?”
This is where an adviser needs to think beyond the amount of life cover.
Joffe’s solution was to use Dollar Life cover to create the foreign-currency liquidity, with a foreign trust as beneficiary and instructions via a letter of wishes to the trustee that the proceeds should first settle the UK tax liability and outstanding bond (if any).
The trust structure also addresses another problem: if the family receives the money directly, there is no guarantee that the money intended for the tax liability will be used for that purpose.
The lesson for the adviser: identify the liability first, then work out what currency and ownership structure are needed to meet it.
The same principle applies when the beneficiaries themselves live abroad.
Joffe described South African parents whose children live overseas. A rand life policy can eventually pay the child on the life assured’s death in South Africa, but getting a large payment out of South Africa can involve tax numbers for the beneficiaries, exchange-control requirements, and additional administration.
“The money will flow to the kid eventually, of course … but it will just take time.”
With the Dollar Life Plan, the proceeds can be paid immediately to a foreign bank account, avoiding that South African forex process at the point of claim.
A big estate can create a big insurance problem
Another example involved a wealthy single client with an estate of more than R100m.
The single status means there is no spousal deduction. Using the figures in Joffe’s example, the estate-duty liability was close to R25m. The Estate Duty Act applies estate duty at 20% on the first R30m of the dutiable amount and 25% above R30m, after the R3.5m basic deduction.
The client could simply buy a rand policy to provide the liquidity. But there’s a problem: the policy itself will have estate-duty consequences.
“You’ve got to sell a R33m policy to clear R25m after duty on the policy to pay the duty. You’re wasting a third of your cover and a third of your premium. Just wasted.”
Joffe’s solution was to use a Dollar Life policy with a foreign trust as beneficiary. There would be a letter of wishes to the trustee to confirm that the proceeds would first be used to settle the estate-duty liability in South Africa, with the balance going to the beneficiaries.
His point was not that every wealthy client needs a Dollar Life policy. It was that advisers should test the structure of the insurance against the liability it is intended to fund.
In this case, he said the client needed roughly R25m of liquidity rather than R33m of cover.
Don’t cancel the policy because the client is leaving
A client who tax emigrates often ends up cancelling South African financial products. Joffe argues that this does not necessarily have to happen with the Dollar Life insurance.
There are two premium routes.
A South African tax resident can pay monthly in rands using the SDA. The SDA allows a South African resident to transfer up to R2m offshore per calendar year, subject to the applicable exchange-control requirements. For the Dollar Life premium route, however, Joffe said Discovery limits the amount to about R1m a year, so that the client does not inadvertently cross the SDA limit. The premium is collected in rands, and the money is sent offshore to Guernsey.
A client who already has money offshore, or who is no longer tax resident in South Africa, can instead pay an annual premium directly in US dollars from an offshore bank account.
Before using the SDA route, the adviser needs to establish where the client is tax resident. That may be harder to pin down than you might think.
Joffe described a client teaching English in Canada who could not even say where she was tax resident.
“We don’t know where they’re tax resident. Often, they don’t know.”
In such a case, he said, the insurer requires confirmation from the client’s lawyer or accountant that they are still tax resident in South Africa. If the client cannot establish South African tax residency, the offshore dollar payment route avoids the SDA question.
More importantly, the client does not necessarily have to start again when leaving South Africa. A client can begin with monthly rand premiums while tax resident here and later switch to annual dollar premiums after moving abroad.
“And for you as an adviser, that’s good news. You keep the client because you’ll often find that when the client’s tax emigrate, all the rand stuff gets cancelled. But now you’ve got a facility to keep the client because this is dollars and not rands.”
That turns pre-immigration planning into an opportunity to review the client’s existing cover before the move, rather than waiting until the client has already left.
Offshore business does not mean a standard offshore solution
Joffe also took advisers into business assurance, where the ownership structure can become more complicated.
One example involved a Hong Kong company owned equally by two shareholders, one living in South Africa and the other in Hong Kong. They needed cover to fund the consequences of either shareholder’s death.
The difficulty was that the shareholders did not have the cash flow to fund the policies personally in dollars.
The solution was for the Hong Kong company to own the policies and pay the annual premiums from offshore, with the insurance supporting a share buy-back arrangement.
Offshore trusts and companies can own Dollar Life Plans for structures such as buy-and-sell, key-person and contingent-liability arrangements. But Joffe repeatedly warned against assuming that more structures produce a simpler solution.
The reason is KYC and anti-money laundering requirements.
A straightforward personal policy may involve one set of checks. Put a Mauritian company above it, three trusts above that, and beneficiaries scattered across several countries, and the insurer has a lot more people and entities to identify.
One of Joffe’s cases involved a Zambian company employing a South African manager. The company was owned by a Mauritian company, which was in turn owned by three Mauritian trusts.
The business had a genuine key-person need. But Zambia is regarded as a higher-risk jurisdiction, and the Guernsey compliance team wanted documentation on the companies, trusts, and beneficiaries.
Joffe’s advice was not to abandon the case, but to understand what you’re taking on.
“These deals are necessary for the client and good business but just expect it to take slightly longer for the extra due diligence required.”
Understand and make provision for the additional due diligence and get the documents together.
Find out early how complicated the ownership structure is, where the entities are based, and who ultimately must be identified.
The South African link can still matter
The fact that an insured person lives outside South Africa does not automatically rule out the cover.
Joffe gave the example of a Rwandan company employing a British national. A South African resident owned 25% of the company, creating the South African connection needed for the case to be considered, subject to underwriting.
He also described offshore business structures where a non-South African shareholder or business partner could be covered because of a clear South African connection, being that of a co-shareholder with a South African.
The point for advisers is to explain the connection when approaching the insurer rather than assuming that “foreign client” means “no”. But the country still matters.
Joffe warned that underwriting and compliance become more difficult in some jurisdictions, particularly where there are additional country-risk considerations.
Offshore cover comes with offshore rules
The Dollar Life Plan is issued through Guernsey, so advisers and clients are dealing with Guernsey compliance requirements, as well as the South African regulatory framework applicable to the insurer.
Joffe said advisers sometimes become frustrated when Guernsey asks for documentation that would not normally be requested in South Africa.
“Certifying a document is much more complicated in Guernsey. You’ve got to say certain words which we don’t use, or they reject it.”
He also warned about third-party premium payers.
Guernsey’s compliance team looks closely at who is paying the premium, the relationship between the parties, and the reason for the arrangement, because they are concerned about potential money laundering.
Advisers should not assume that a legitimate South African arrangement will automatically be understood by an offshore compliance team. If something looks unusual, expect them initially to ask for an explanation, although now they are starting to understand South African structures much better.
Putting the pieces together
Joffe’s cases covered London property, children abroad, estate duty, Hong Kong business interests, clients preparing to leave South Africa, and key people in Africa.
The circumstances differed, but the adviser questions were much the same:
- Where is the client now?
- Where will they be living?
- Where are the assets and liabilities?
- What currency will be needed?
- Who needs to receive the proceeds?
- Who will own the policy?
- Who will pay the premium?
- What documentation will the insurer need to see?
- What are the tax and estate duty consequences in SA?
The Dollar Life Plan is one answer to some of these questions, particularly where the client needs genuine offshore risk protection. But the broader point from Joffe’s presentation was to identify the planning problem early and work through the practicalities before promising the client a solution.
That means understanding the client’s tax residency, the location of the assets and liabilities, the currency in which the money will ultimately be needed, the ownership and beneficiary structure, and what the offshore insurer will require from a compliance perspective. Also understand the tax consequences on both sides.
“Just make sure you understand the South African link and the payment methods.”


