When SARS oversteps, how can taxpayers fight back?
Complex legislation, estimated assessments, and collection measures can leave individuals and smaller businesses struggling to challenge SARS effectively.
Complex legislation, estimated assessments, and collection measures can leave individuals and smaller businesses struggling to challenge SARS effectively.
The Institute for International Tax and Finance says Clara can indicate when SARS approval may be required and which supporting documents users may need.
The judgment considered Bidvest’s contractual authority to suspend the account separately from SARS’s subsequent use of section 179 of the Tax Administration Act.
The standalone system introduces new registration, seller relationships, and record-keeping requirements.
Two aspects of the judgment could have wider implications in future cases involving credible claims of unauthorised access.
The majority judgment confirms that raising fees can qualify as finance charges similar to interest, potentially reducing the after-tax cost of debt funding.
The shift to near real-time reporting promises better fraud detection and faster refunds, but businesses face significant technology costs and implementation challenges.
Treasury wants to close what it sees as a tax-avoidance route involving emigrating spouses, while proposing a taxpayer-friendly change to voluntary disclosures.
The proposal puts SARS’s existing cumulative approach into the Income Tax Act, ending uncertainty over whether the R150 000 limit applies per policy.
Experts say taxpayers with undeclared crypto income should consider voluntary disclosure before enhanced reporting increases the likelihood of a SARS audit.
The Tax Court has affirmed the choice principle but raised fresh questions about where legitimate tax-efficient structuring ends and impermissible avoidance begins.
Practitioners warn that applying section 7(8) to cross-border trust distributions could create onerous and potentially perpetual tax and compliance consequences.
The High Court finds that most of the payment was a recoverable, interest-bearing deposit rather than expenditure incurred for genuine insurance cover.
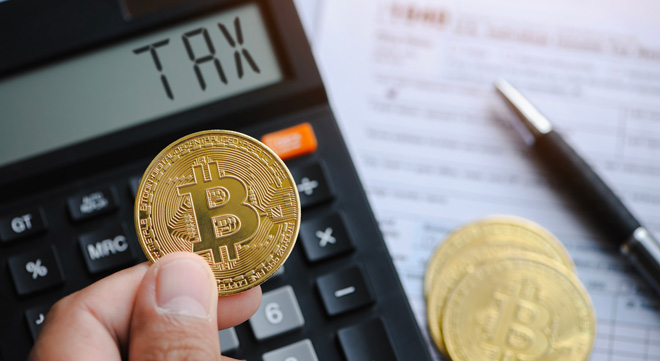
Crypto users may trigger tax consequences through swaps, staking, mining, payments, employment benefits, or donations, even where no rand conversion takes place.
Trustees face growing pressure to file outstanding returns or formally deregister dormant trusts before penalties escalate.
Companies are under growing pressure to prove that the figures in returns, financial statements, and supporting documents all tell the same story.
The new APA process aims to reduce disputes and double taxation, but practitioners say the entry bar is so high that few groups will qualify.