South Africa’s two-pot retirement system is recognised as a positive reform in the 2026 Marsh CFA Institute Global Pension Index because it protects two-thirds of new contributions for retirement. But household debt is already driving members to access their savings, and the full effect of the preservation rules will take time to emerge.
The reform, which took effect on 1 September 2024, divides net new retirement fund contributions between two components. One-third goes into a savings component, which members can access while working, subject to the rules. The remaining two-thirds goes into a retirement component and must be preserved until retirement.
Savings accumulated before the reform remain in the vested component. The legacy withdrawal rules generally continue to apply, less the seed capital transferred to the savings component.
The Index notes that protected contributions will build over time, including when members change jobs. Previously, employees could withdraw their full retirement fund benefit when leaving employment.
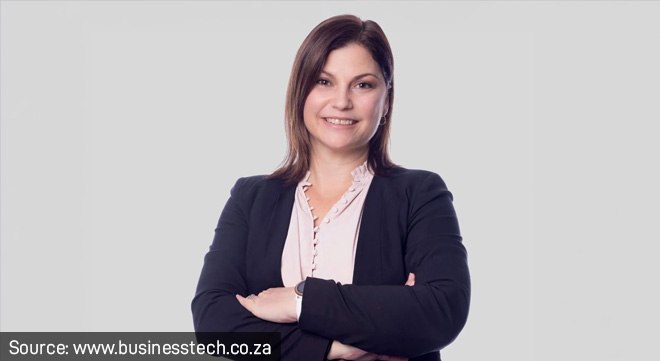
Belinda Sullivan (pictured), head of corporate consulting strategy at Alexforbes, said the compulsory preservation element should improve outcomes for people who belong to occupational retirement funds.
“Rather than taking money every single time that they leave, now into the future, they will always have that two thirds that will be preserved for them that they won’t be able to access,” she said during a briefing on the Index.
Debt is driving withdrawals
Sullivan said members are already accessing their savings component because they are struggling to make ends meet.
“With our introduction of two pot, we do see people accessing their savings component largely driven by the fact that they are struggling to make ends meet, and there’s debt that’s driving the pressure that they’re experiencing,” she said.
The Index also identifies household affordability and indebtedness as constraints on retirement saving. Past withdrawals and interrupted careers are listed among the factors that erode retirement balances.
Sullivan said it remains too early to know whether members will use the savings component mainly for emergencies or come to regard it as money available to withdraw each year.
“We can do projections, and we can look at where are we and what is the expectation. But I think time will really tell us what the improvement is in terms of those outcomes,” she said.
The legacy effect
Members can still access savings accumulated before the reform under the previous rules. Sullivan described this as a “legacy hangover”, which means the full effect of compulsory preservation will take time to work through the system.
As older savings are depleted and more contributions accumulate under the new rules, the preservation benefit should become clearer. Sullivan expects two-pot to improve future retirement outcomes and replacement ratios but says this has not yet filtered through into the figures.
Alexforbes’ member insights, based on about 1.1 million active contributing records, showed an average actual replacement ratio of 40%, compared with an expected average of 46%. These figures do not yet reflect the impact of two-pot.
The coverage gap remains
The Index identifies voluntary occupational coverage, household affordability, low incomes and limited provision for informal workers and the self-employed as weaknesses in South Africa’s retirement system. Two-pot does not extend retirement fund membership to people outside occupational funds.
Sullivan suggested affordability-based auto-enrolment as one way to bring more employees into retirement saving, potentially starting with lower contributions that increase over time.
She also urged employers and trustees to review contribution levels and improve member communication and support.
“We need coverage. We need to look at the irregular earners, so people who are perhaps freelancing. You know, what do they do with their savings? How do we pull them into the net? How do we help and support them?”