The proposed Synthetic Financial Centre (SFC) could help South African institutions compete for global investment mandates and build a wider domestic industry around managing international portfolios.
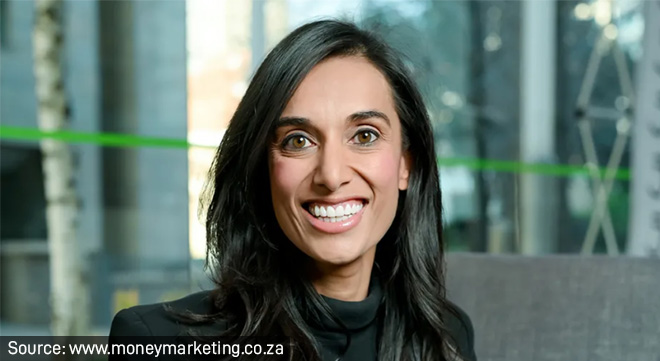
Valdene Reddy (pictured), JSE Group chief executive and chairperson of Operation Phumelela, said the potential benefits extended beyond asset management. South Africa could develop additional expertise and activity in investment research, trading, custody, administration, banking, and private markets.
“It is far more than just the management of offshore assets that could now come to some of our South African financial institutions,” she told a webinar hosted by Krutham on 23 October 2026.
“You can extend and build out research, trading, custody, and other administrative services. Different institutions will stand to benefit, not just asset managers who can now compete for global mandates, but our banks could expand their foreign-currency financing and services.”
The webinar followed the South African Reserve Bank’s publication of the draft SFC circular for public comment. The proposed framework would allow qualifying institutions to manage foreign-asset portfolios and conduct approved foreign-currency activities from South Africa through ring-fenced arrangements.
As Moonstone previously reported, an existing financial-services licence would not automatically confer participation. Institutions would have to register with the SARB’s Financial Surveillance Department (FinSurv), obtain the relevant approval, and meet the proposed operational and reporting requirements.
Read: SA plans framework to attract global investment-management business
Krutham, a financial research, advisory, and policy firm, serves as the secretariat to Operation Phumelela, a private-sector financial-sector competitiveness initiative. Dr Stuart Theobald, Krutham’s executive chairperson, convenes the taskforce. The taskforce says it developed the SFC concept during two years of engagement with National Treasury and the SARB.
Benefits across the financial-services value chain
Reddy said insurers and retirement funds could gain additional choice and potentially lower costs from having products and expertise available locally. Private-market managers could pool capital for investment across Africa.
She did not expect the SFC to result in a single, sudden return of offshore assets.
“I don’t think it’s one inflection point,” she said.
One opportunity would be to recover mandates that had moved to offshore managers. South African institutions could also compete for international assets they had not previously managed.
Later phases could broaden the opportunity. Reddy referred to foreign-currency capital raising and the prospect of a wider range of international products being traded and settled in South Africa.
“The potential becomes a lot bigger,” she said. “It makes us think of South Africa now as a globally competitive capital market, and not just an exchange-control reform for South Africa.”
Reddy encouraged institutions to identify commercially viable activities, develop differentiated international offerings, and assess the skills and operational capabilities they would require.
The originating institution’s 45% limit will remain
Olano Makhubela, head of FinSurv, said the 45% prudential foreign limit would continue to apply to the domestic originating institution allocating money to an SFC portfolio.
The limit would not determine the foreign composition of the approved portfolio. An SFC manager could operate a portfolio consisting entirely of foreign exposure.
Theobald described an SFC manager holding a fully foreign portfolio and reporting its composition to the originating institution. This would enable the originating institution to look through the portfolio and recognise the exposure against its own applicable prudential limit.
The draft circular adds the regulatory detail. Foreign exposure acquired through an approved SFC mandate remains attributable to the investor on whose behalf it was acquired. It continues to be recognised against that investor’s applicable limit or allowance.
The exposure does not count against the SFC participant’s own prudential or macroprudential limit unless the participant acquires it for its own account.
A retirement fund, insurer, or other originating institution could therefore not use the SFC to exceed its permitted foreign exposure. The regulatory change would enable an approved South African manager to run a fully foreign portfolio on the institution’s behalf without using the manager’s own prudential foreign capacity.
Makhubela said the SARB regarded the originating institution’s allowance as a prudential and financial-stability measure. The central bank did not view it merely as an exchange-control restriction.
“It serves a stability purpose. It serves a prudential purpose. And so, even if we end up […] under a new capital-flow management regime, that allowance will still be there,” he said.
Makhubela said SARB research indicated that the allowance could assist during “sudden stops”, when capital flows reversed. A domestic pool of funds could absorb excess selling and help to manage market prices.
He separately identified the currency risk associated with foreign assets. When the rand strengthened, the rand value of those assets declined. Institutions had to take this risk into account when investing offshore.
Makhubela said the SFC should be able to operate under the present framework without waiting for the proposed wider capital-flow management regime.
The 45% figure does not apply universally to every potential SFC investor. Authorised dealers would invest subject to their applicable macroprudential foreign limits. Individuals would use their applicable foreign-capital or single discretionary allowances.
The draft also permits incidental South African exposure within a predominantly foreign SFC portfolio. South African assets would retain their domestic classification rather than being treated as foreign merely because they were included in the portfolio.
No lighter regulatory regime
Vukile Davidson, National Treasury’s chief director for financial-sector policy, said phase one of the initiative had deliberately been designed to operate within South Africa’s existing legislative and regulatory framework.
“In relation to phase one […], we don’t anticipate any need for legislative amendments to enable this. We think that this operates within the existing framework. That’s not an accident. It was designed to work within the existing framework,” he said.
Most potential participants would already be licensed and regulated by the Financial Sector Conduct Authority, the Prudential Authority, or another relevant regulator.
“The intensity and the nature of those regulations will be carried on into the SFC space. It’s not like there is a lighter regulatory regime applicable in the SFC space,” Davidson said.
The same customer protections would apply to conventional domestic business and approved SFC activity.
National Treasury regarded the existing architecture as appropriate for phase one. The greater complexity of subsequent phases could require legislative amendments.
Makhubela said the “heavy lifting” on phase one had been done through the draft circular. The SARB had consulted within the regulatory community and tested elements of the framework with some market participants.
“We are very much open to hearing from you and fine-tuning the circular where we can,” he said.
Prospective application process
Once the framework is finalised, the SARB intends to issue a standard application template.
“There should be a template that we will put forward, which should also assist so that we standardise how the application should be captured,” Makhubela said.
Many prospective participants would already be licensed or registered with the FSCA, the Prudential Authority, or the SARB.
SFC registration would provide FinSurv with information about activity conducted under the framework. It would also enable the department to monitor compliance with the relevant limits and allowances.
“We’ll try and keep it as seamless as possible. We are now working with a 30-day turnaround once we get the application,” Makhubela said.
The draft circular does not establish the 30 days as a statutory deadline. It does not specify when applications will open or when the turnaround period will begin.
The circular treats registration as an eligible participant and approval for specified SFC activities or arrangements as related but distinct requirements.
Tax alignment under consideration
Theobald asked how the SFC framework would align with tax treatment where institutions operated in a foreign functional currency.
Davidson said work on complementary frameworks, including tax, was already under way. National Treasury would assess the implications and design an appropriate response.
Operating infrastructure still being developed
Theobald said the SFC’s operating model remained a live question.
Industry working groups were considering custody and settlement. They were also considering how existing foreign-asset operating arrangements could be integrated.
“The working groups are working on the plumbing and what can be integrated now from custody, settlement questions, and so on, and what will be phased in over time,” he said.
International connectivity, passporting, and foreign-market recognition also require further consideration.
The draft identifies non-rand listings, investment-vehicle domiciliation, market infrastructure, and related legal and tax reforms as possible matters for phase two. They are not features established by the first-phase framework.
Davidson separately addressed South Africa’s cross-border payment costs. He said the SFC could reduce some transaction friction at the margin but would not solve the wider problem.
Broader payment-system reforms would be required. He also referred to the need for more proportionate anti-money laundering and counter-terrorist financing frameworks.
The draft circular is open for comment until 30 November 2026. The SARB will consider the submissions and make revisions where appropriate.