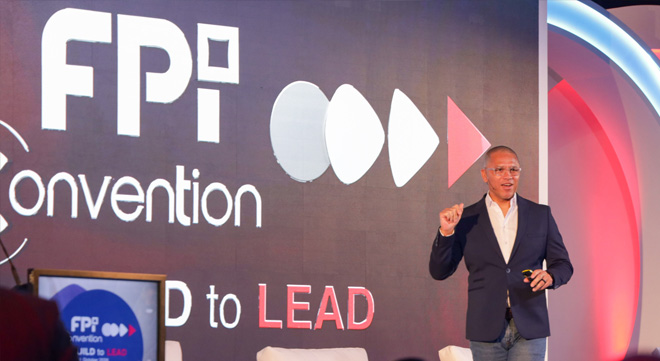
The greatest risk facing financial advisers was not simply replacement by artificial intelligence, but that the definition of financial advice could change faster than they adapted to it, says Stafford Masie, technology entrepreneur and former Google South Africa country manager.
At the FPI Professionals Convention on 8 October 2026, Masie argued that AI was making intelligence, information, and analytical capability increasingly abundant. Advisers therefore needed to think more carefully about the difference between the activities they performed and the value clients ultimately paid for.
For most of their careers, he argued, financial planners operated in a world where information and expertise were relatively scarce. Clients often relied on advisers to obtain information, interpret it, and explain its significance. As AI makes both intelligence and information more widely available, he said, professionals must identify what remains valuable when those resources are no longer difficult to obtain.
His challenge to advisers was to distinguish between what they do and the value they create.
“Never confuse what you do with the value you create.”
Masie argued that planners should not assume that information, portfolio analysis, or technical calculations are the primary reasons clients engage them.
He said advisers ultimately provide judgement, confidence, behavioural intervention, accountability, trust, and help with decisions made under uncertainty. As information becomes easier to obtain, those qualities become more important rather than less.
Masie described his own relationship with financial advice. AI already provides him with information, performance data, and analytical insights. Yet he still sees value in speaking to a planner when making important life decisions, because his adviser understood him in ways that technology could not easily replicate. She knew his family, his ambitions, his behaviour, and the context in which financial decisions were made.
Clients may expect advice to move faster
Masie argued that AI was changing expectations around time.
He said AI could compress the time between an interaction and the delivery of useful information. He suggested that clients may increasingly expect advice to be delivered as a continuous flow of information rather than through quarterly meetings alone.
In his view, advisers should consider how AI could enable them to provide analysis, forecasts, and follow-up information during or immediately after a client engagement.
More broadly, he argued that the profession was moving from financial planning as a periodic event towards financial intelligence as an ongoing condition, with information and support available more continuously than before.
The competition may be adviser-plus-AI
Another theme running through the presentation was that the most significant competition may not come from AI acting independently.
Masie referred to the concept of “centaur” intelligence, in which humans and machines work together rather than competing directly. He argued that the strongest results would come from combining human judgement with machine capability rather than relying entirely on either.
He argued that the profession’s future competition may come less from AI acting independently than from advisers who learn to combine human judgement with machine capability.
Masie also challenged advisers to reconsider how they spend their working day. He estimated that much of their time was devoted to gathering and collating information. Technology, in his view, should remove much of the information gathering, collation, and administrative effort surrounding advice. The objective was not to eliminate human interaction but to create more capacity for interpretation, judgement, and client engagement.
One life, not separate financial and personal lives
Masie highlighted the distinction between technical advice and the broader questions clients are trying to answer.
“Nobody wakes up thinking I really need a beautifully optimized multi-asset portfolio today,” he said.
Instead, clients are more likely to ask whether they can retire, support their children, navigate uncertainty or achieve the life they want. Financial decisions form part of those questions, but they are not usually the questions themselves.
Masie argued that clients do not have separate financial lives and personal lives. They have one life, and money merely flows through that life.
He concluded by challenging advisers to think carefully about what remains distinctive when information and analysis are widely available.
“What part of your job is still worth paying for?”
In Masie’s view, the answer lies less in access to information than in helping clients interpret it in the context of their lives.