Private markets promise investors access to the parts of the economy that never make it onto a stock exchange. But opening that door in South Africa comes with a difficult trade-off: how do you give investors access to illiquid assets without making them look more liquid than they really are?
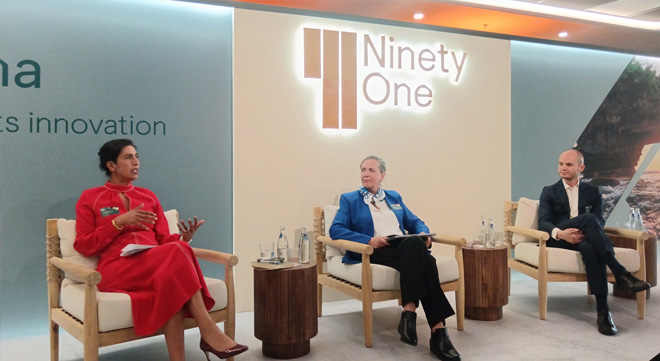
The topic was explored at Ninety One’s Beyond Alpha event on 17 September 2026. A panel discussion on “Democratising private markets” brought together Nazeera Moola, chief commercial officer: private markets at Ninety One; Nicola Brink, head of financial stability at the South African Reserve Bank; and Dino Zuccollo, head of investor solutions at Westbrooke. Eugene Booysen, chief executive of the Cape Town Stock Exchange, also offered insights into the role exchanges could play in broadening access to private-market investments.
Private markets cover investments outside traditional listed markets, including private equity, private credit, infrastructure, and real estate. Private credit alone has grown into a market estimated at between $1.5 trillion and $2 trillion (approximately R25 trillion to R33 trillion) globally. It is now comparable in size to the US high-yield market and has become a significant allocation for institutional investors, while access is increasingly moving into the wealth and retail markets.
Unlike shares or bonds traded on an exchange, private-market investments are generally harder to value and sell. That has implications for how investors access their money, how funds manage withdrawals, and how regulators monitor risks building up in the financial system.
South Africa’s experience is different.
South Africa is not the US
The global growth of private credit was partly driven by changes in the banking system following the global financial crisis. Higher capital and liquidity requirements made some forms of long-term lending more expensive for banks, creating space for non-bank lenders. Brink described this as a form of disintermediation: lending that might previously have been provided by banks moving towards non-bank financial institutions.
South Africa has not followed the same trajectory.
Local banks remain significant providers of capital to businesses that private-credit managers might typically finance in developed markets. They also have relatively high levels of liquidity, giving them capacity to continue lending.
“It’s actually really difficult to build a private credit business in South Africa because the banks are so good,” Zuccollo said. He described local banks as having learnt to “fish in a small pond”, competing for loans that private-credit managers might otherwise provide.
He said his firm’s local private-credit fund had been refinanced several times by banks during the year, with loans in the R50 million to R250 million range. The banks have a cheaper cost of capital than private funds and are willing to compete for this business.
Moola said Ninety One had seen a similar dynamic, with its roughly R20 billion South African private-credit build-out involving partnerships with banks on transactions where the banks did not want to take all the risk.
That makes the South African market quite different from the US and UK, where private credit has moved into lending segments that banks have increasingly stepped away from.
It also helps to explain why the risks attracting international attention are not yet evident at the same scale locally.
“I just think that the South African private credit market in size … is small,” Zuccollo said. “I don’t necessarily see the same level risks yet, unless things change materially in the future.”
The problem with not knowing
The market may be small, but much of it remains difficult to measure.
“We think it’s small. We believe it’s small, but we don’t actually know,” Brink said.
The SARB recently participated in an international comparison in which South Africa came out as a small private-credit market. But Brink said South Africa was unable to provide much of the data supplied by other jurisdictions.
For the SARB, the concern is not a loss carried by an individual investor. Systemic risk becomes more relevant when private funds are connected to banks through loans, liquidity facilities, or other forms of leverage.
“If there’s stress, even undrawn facilities may suddenly be drawn and cause a liquidity event in banks,” Brink said.
South Africa has limited direct bank exposure to private credit. The concern is the less visible leverage sitting around the market.
Moola said estimates from the US and parts of Europe put bank lending to private funds, through credit lines or fund-level leverage, at between $350bn and $500bn (approximately R5.9 trillion to R8.4 trillion) – a substantial proportion of the global private-credit market. South Africa, she said, is “quite far away from that”.
Moola said Ninety One’s experience in emerging markets is that lenders can still negotiate stronger covenants and lower leverage than is increasingly common in developed markets. The problem, she said, is that international investors can view those same emerging-market characteristics as a risk rather than a protection.
An additional source of capital
Brink described South Africa as “an investment-hungry country”, pointing to the limits of the banking system and the fact that South Africa does not have the depth of market-based finance available in many advanced economies.
Private markets could provide another channel for capital to reach businesses and other investments.
The attraction for investors is broader than potential returns.
Zuccollo pointed out that between 87% and 90% of businesses globally generating more than $100m (approximately R1.7bn) in revenue are privately owned. An investor whose portfolio is concentrated entirely in listed markets is therefore not necessarily exposed to the full breadth of the global economy.
He sees private credit primarily as a diversification tool and, depending on the manager and strategy, a potential return enhancer because its performance need not move in lockstep with traditional markets.
The trade-off is liquidity.
The underlying assets can be difficult to sell quickly, and their valuations may not be observable every day. Investors may have to accept that their capital will not always be available on demand.
Liquidity is not a promise
For retail investors, the question of liquidity becomes harder to avoid.
Europe’s European Long-Term Investment Fund (ELTIF) and the UK’s Long-Term Asset Fund (LTAF) are examples of structures created specifically to provide wider access to private assets.
Zuccollo said the first version of ELTIF did not work particularly well, but the subsequent ELTIF 2.0 framework has grown to €34bn (approximately R670bn) across 280 funds. The framework provides rules around eligible assets, diversification, investor protection, and liquidity, creating a structure through which private markets can be offered to retail investors.
Some of these funds are open-ended, meaning they do not have a fixed end date, or evergreen, meaning they are designed to continue operating indefinitely. They can offer investors opportunities to withdraw their money at set intervals, but those withdrawals are subject to defined limits. Zuccollo said roughly a third of European ELTIFs are focused on private credit, partly because the regular cash flows from lending can help to support these periodic withdrawals.
That does not mean investors can demand their money whenever they choose.
“We have to normalise the concept of gating as a feature of the vehicle,” Zuccollo said. “It’s not like the credit fund is blowing up because investor redemption requests exceeded the available liquidity in the vehicle.”
A private-credit fund holding long-term loans cannot meet unlimited redemption requests without potentially selling assets under pressure.
“A bank promises deposit holders their money tomorrow if they want it out,” Zuccollo said. “A private credit fund does no such thing.”
Brink put the trade-off more simply: “You get an illiquidity premium on your investment.”
South Africa’s product problem
South Africa’s existing investment structures were not all built with private assets in mind.
Zuccollo described this as one of the biggest challenges facing private-market managers locally. The options include collective investment schemes, securities, companies, partnerships, and direct loans, but the regulatory and liquidity requirements differ between them.
A collective investment scheme, for example, brings liquidity and reporting requirements that can be difficult to reconcile with private assets. Qualified-investor funds also have minimum investment requirements that are not suited to the broader market.
“We are constantly fitting squares into circles here,” Zuccollo said.
The result is a fragmented market in which investors do not always receive information in a consistent format, and managers have limited purpose-built options for packaging private assets.
There is also a regulatory mismatch that extends beyond retail investors. A question from the floor pointed to the fact that the Pension Funds Act permits exposure to private markets while collective investment scheme structures do not always accommodate the same assets. The response was that harmonisation is one of the challenges being considered.
The international frameworks provide examples, rather than templates that South Africa can simply copy.
Zuccollo’s argument is that access to private markets is expanding regardless of whether the regulatory framework is ready for it.
“I don’t know if it matters,” he said, when asked whether he was in favour of democratising private markets. “In my opinion, it’s happening. So rather have an enabling regulatory environment to protect investors when it does happen.”
Listing does not make an asset liquid
That gap has already encouraged market participants to look for workarounds.
Zuccollo said some private-market managers are using listed notes that reference illiquid underlying assets. He questioned why an investment structure can hold an illiquid small-cap listed share while a private-credit fund with contractual cash flows can face greater restrictions.
Booysen sees a role for exchanges, but not because a listing can manufacture market liquidity.
An exchange can provide contractual liquidity and greater disclosure. A listed instrument has defined terms, a formal transaction mechanism, and disclosure about the underlying structure.
Booysen compared actual market liquidity to a movie theatre: “Whenever you need it, someone shouts fire, everyone gets in orderly, until someone shouts fire, and then everyone’s trapped.”
The distinction matters. A listed instrument can create a clearer mechanism for buying and selling, but it cannot guarantee that a buyer will be there when an investor wants to exit.
Booysen also pointed to the standardisation and disclosure that come with listed structures. Zuccollo noted that his firm’s offshore vehicles can obtain an ISIN even when they are not listed, giving platforms a recognised framework for compliance and governance that is harder to achieve locally.
Technology can lower the barrier
Zuccollo said tokenisation can reduce the cost of setting up and distributing investments, which in turn can bring down the amount investors need to put in.
“Tokenisation … reduces costs of implementation and therefore helps reduce the minimum investment ticket that is required to gain access,” he said.
But cutting an investment into smaller digital units does not make the underlying asset liquid.
“I don’t think it solves the problem that we’re discussing here,” Zuccollo said.
The technology could, however, be used further down the investment chain. If the underlying loans themselves are tokenised, they can potentially be transferred more easily, creating a secondary market where investors can trade their interests rather than waiting for the underlying loan to mature.
Private credit is already one of the fastest-growing segments of the on-chain market. Tokenising loans at source could allow funds to trade in and out of those instruments more easily and potentially create liquidity where underlying loans would otherwise be difficult to sell.
Moola pointed to another potential benefit. A borrower does not necessarily want to contract separately with several funds and a manager. A tokenised structure could provide a single entry point while allowing interests in the underlying investment to change hands further up the chain.
For Zuccollo, there could also be an operational benefit for growing managers. Tokenisation may help to move some of the onboarding and KYC burden further along the investment chain, reducing the infrastructure a manager needs to build itself.
The technology may change how investors access, hold and transfer a private asset. It does not, however, change the credit risk of the underlying loan.
The case for better data
Private assets do not have the same degree of standardisation as public-market investments. Zuccollo said investors often ask whether individual private loans have been credit-rated as a way of finding a common measure of risk.
“I don’t think the issue is the availability of information,” he said. “I think it’s the way that it’s put together and standardised.”
The Financial Stability Board is working on standardising the definition and classification of private credit and developing reporting frameworks that could eventually be adapted by jurisdictions such as South Africa.
The South African framework will need to be proportionate. Moola warned that collecting enormous quantities of data can become a regulatory box-ticking exercise if investors and regulators cannot use it effectively. Brink agreed that South Africa should be able to take what is useful from international frameworks without simply adopting every requirement.
Building the market
Brink said broader retail access could offer “huge opportunity”, provided there is transparency and oversight. But she cautioned against assuming that a listing automatically creates liquidity.
“I don’t think liquidity is automatic,” she said.
For the SARB, the more immediate concern is understanding how the market is developing and where exposures are accumulating.
“I would plead for data so that we know who owns what and who’s exposed to what,” Brink said.