Insurers face a more demanding liquidity framework
The draft standard replaces the existing liquidity risk assessment standard with more comprehensive requirements for managing, monitoring, and reporting liquidity risk.
The draft standard replaces the existing liquidity risk assessment standard with more comprehensive requirements for managing, monitoring, and reporting liquidity risk.
Financial institutions, insurers, and other direct marketers have until 6 November to comment on proposed guidelines setting out their compliance obligations.
The Authority’s three-year roadmap also outlines upcoming reforms affecting financial markets, retirement funds, payment services, and cross-sector regulation.
The extension preserves the existing framework allowing qualifying juristic representatives to collect and deal with insurance premiums on behalf of insurers.
The revised draft standard sets out detailed qualitative and quantitative public disclosure requirements and is open for comment.
Rapid, transparent claims processing and simplified policy wording are key to building trust. Firms that demonstrate protection consistently can contribute to a resilient market.
DataEQ’s 2025 Index shows that insurers’ positive brand campaigns are undermined by operational weaknesses in claims, billing, and responsiveness.
South Africa now has a publicly available Climate Index, developed by actuaries and meteorologists, that tracks extreme weather events.
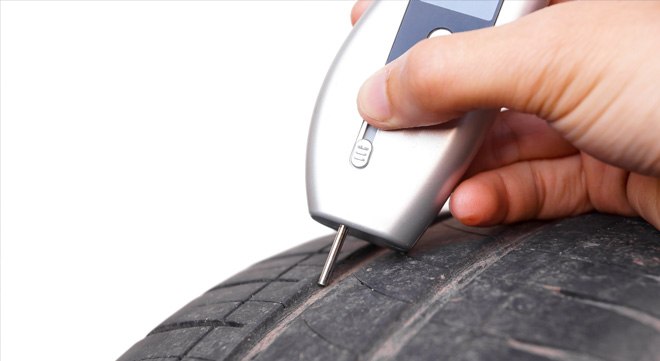
While insurers can decline claims involving unroadworthy vehicles, repudiations must be linked to the cause of the loss.
The ruling requires insurers to plead subrogation and join as parties in civil actions, departing from long-standing practice that allows insurers to step into their insured’s shoes without separate citation.
Roleplayers in the funeral industry can book for an online workshop hosted by the FSCA and the Prudential Authority.
Although expropriation itself is generally an excluded event, there may be knock-on effects that could impact the insurance sector.
The standard, which replaces GOI 5, governs outsourcing by insurers from a prudential and a conduct perspective.
Banks and insurers are expected to treat climate risk as a financial risk rather than merely a reputational risk event.
The requirements for advice fees in the context of insurance policies will be dealt with by amending the insurance regulations.
To assist the Financial Sector Conduct Authority (FSCA) in obtaining better insights into the current processes and practices used to market and sell add-on insurance policies at motor dealerships to customers, the FSCA […]
South African insurers have struggled to keep up with increased customer demands during the Covid-19 crisis. This was one of the take outs of an assessment of the South African insurance industry by […]