An estimated $18.3 trillion will be transferred between generations globally by 2030. Yet research cited by Kenny Rabson, the chief executive of Discovery Invest, suggests that without a plan to preserve it, 90% of wealth is lost within three generations.
What if more of that wealth could be retained?
Discovery Invest believes financial advisers have a role to play. But keeping wealth in the family takes more than managing one person’s investment portfolio. It means understanding how family members’ finances fit together, planning for their different needs, and building relationships that last beyond the person who first accumulated the wealth.
That is the thinking behind the Family Wealth Consolidator, launched by Discovery Invest in October. It brings eligible family members’ investments together, allowing them to benefit from combined asset values for fee purposes and giving them a consolidated view of their investments. A redesigned digital platform also gives investors and advisers a broader view of family finances and helps to identify potential financial-planning opportunities.
“So, it’s really how do you optimise that and make sure that it lasts for the family into the future?” Rabson said.
There are financial incentives too. These include lower administration fees when qualifying assets are combined, Vitality Money paybacks on eligible asset management fees, and reduced fees on certain investments held for children. Depending on how the family structures its investments, there may also be estate planning and tax benefits.
When wealth changes hands, the adviser relationship often doesn’t
Why does so much family wealth disappear between generations?
Research commonly cited in wealth management suggests that 70% of family wealth is lost by the second generation and 90% by the third.
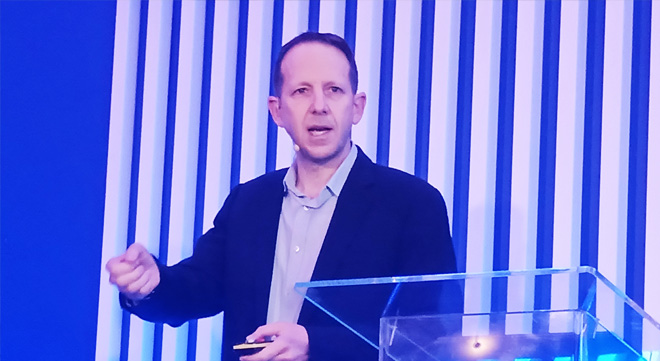
Craig Sher (pictured), chief product and investment officer at Discovery Invest, says there is no single reason. Wealth is divided among beneficiaries, some inherit money without the experience to manage it, and others do not have access to appropriate financial advice.
“The biggest reason is probably a lack of education or advice, which results in people not knowing how to manage the wealth they’ve inherited,” he says.
People are also living longer, which means inherited assets may need to support them for many more years. Poor estate planning can add to the problem, with taxes and other costs eating into what is passed on.
The relationship between families and their financial advisers presents another challenge. Rabson cited research showing that only 19% of affluent investors use the same adviser as their parents. He sees this as an opportunity for advisers to build relationships with the wider family, rather than focusing only on the person who accumulated the wealth.
That could make a difference when assets are passed on. Advisers who work with family networks may be better placed to retain those assets and advise on a larger pool of investments. Rabson cited global research suggesting that advisers who work with families could advise on more than twice the assets of those who focus on individuals.
Sher believes those relationships should be built well before an inheritance becomes an issue. He also points to a more immediate challenge: couples where only one person is advised or even where different advisers are used, even though they share financial goals and will eventually rely on a combined retirement income.
He described a situation in which a husband and wife each have an adviser and plan for retirement separately. One adviser may recommend and be comfortable to manage the assets in a living annuity, while the other adviser prefers a fixed annuity. Yet the couple is likely to retire together and draw on the same household resources.
“The combined strategy actually needs to be formed by a single view, as opposed to being formed by advisers with different outlooks,” Sher said.
The same thinking applies to investment allocation, tax and estate planning. Separate portfolios can end up holding similar investments, while opportunities to use each family member’s tax allowances or make donations to children may be overlooked.
People are also living longer, so it is now quite possible for grandparents, parents, children, and grandchildren to be alive at the same time.
But their financial needs can be very different.
“Everyone’s got a different time horizon. You could be looking at kids who need money for university, people saving for retirement, older people that need conservative shorter-term investments,” Rabson said.
“There are different liquidity requirements across the family,” he added, explaining that advisers need to consider when each family member will need access to their money and how those needs fit into the family’s overall financial plan.
A clearer view of the family’s investments
Alongside the Family Wealth Consolidator, Discovery Invest has redesigned its client website to give investors a clearer view of their portfolios.
Clients can see the total value of their investments, track growth against contributions, and follow cash flows. They can also look inside their funds to see how their money is spread across asset classes, local and global markets, and underlying investments.
Advisers have the same consolidated view through Advisor 360, making it easier to see how the family’s investments fit together.
The platform also flags potential financial planning opportunities using information held across Discovery’s businesses. These include possible retirement contribution tax deductions, annual donations to children’s investments, and opportunities to preserve retirement savings when a member leaves employment. It can also identify family members who may not be using their full single discretionary allowance for offshore investments.
The opportunities appear in Advisor 360, where advisers can share them with clients. Sher said that the functionality is not strictly artificial intelligence: it uses information already available within Discovery’s businesses to flag circumstances that may warrant a conversation. The adviser still needs to assess the client’s circumstances and provide appropriate advice.
Advisers also have access to a tool called the Family Evaluator, which allows them to model the potential financial benefits of consolidating a client’s family investments. By entering the family members’ details and their assets, the adviser can project the value of fee aggregation, Vitality Money paybacks, and investment boosts over the investment term. It gives the adviser a way to put figures to the potential benefits and show a family what the structure could mean for them over time.
Getting the family into one group
A family group can be created by either the principal investor or their financial adviser through the Discovery Invest website. Once the group has been set up, the principal investor receives a unique code by SMS, which can be shared with the family members they wish to invite.
Each invited person enters the code on their side and decides whether to join. The request then goes back to the principal investor, who approves the membership.
As Sher explained: “If I want to create a family and I want you to join my family, I send you the invite. You accept it or not.” Both parties must agree; nobody can be added without their consent.
A group can have up to 10 members. The eligible categories include a spouse or partner, children (including adopted, step- and dependent children), parents, and certain family trusts and companies. Each person may belong to only one family group.
Sher said the relationship does not necessarily have to be by blood. A life partner, for example, can be included even if the couple is not married.
By joining the group, members agree to share information about their investments with the principal investor. Sher explained that the principal investor can see the assets held by the other members but not the other way round unless this is separately shared. The principal cannot transact for other family members.
A person can leave the group, and the principal can remove a member if circumstances change. The fees are then adjusted to reflect the change in the group’s qualifying assets.
Once the members are in, their qualifying investments are brought together in a consolidated family report. The combined assets are used to calculate the family’s administration fee, potentially moving members into lower fee bands as more qualifying investments are added.
How the fees and rewards work
According to Sher, the discounts associated with the Family Wealth Consolidator product make Discovery Invest “the cheapest place to get asset management”, including on offshore funds.
The two main benefits are lower administration fees when family members combine their qualifying assets, and Vitality Money paybacks on eligible asset management fees.
The administration fee is based on the family’s combined qualifying investments on the platform, rather than each member’s assets being assessed separately. As the total grows, the family can move into lower fee bands. Bringing a spouse, children or parents into the group could therefore reduce the administration fee payable.
Vitality Money paybacks reduce the asset management fees on eligible investments, with the percentage depending on the family’s qualifying assets and each investor’s Vitality Money status. The highest paybacks apply to qualifying Discovery and Cogence funds, while lower paybacks are available on eligible third-party funds.
Sher illustrated this with a family holding between R5 million and R10m in qualifying assets and having Gold Vitality Money status. In that example, the family could receive a 20% payback on qualifying Discovery and Cogence funds and 10% on eligible third-party funds. The amount a member receives will depend on the applicable requirements and their own qualifying status.
Children’s investments have an additional benefit. Qualifying investments in a child’s name can receive a 50% reduction in asset management fees. This increases to 100% for families with more than R5m in qualifying assets.
The children’s benefit applies to qualifying Flexible Investment Plans and Tax-Free Investment Plans, with a combined annual investment limit of R300 000 across all children in the family group. When the child turns 18, he or she reverts to the normal Vitality Money PayBacks of up to 30%.
Not every investor will qualify for every benefit. Vitality Money paybacks require active Vitality Money membership and a qualifying Discovery Bank relationship. Clients do not need to belong to Discovery Health or Vitality to join the Family Wealth Consolidator, but the additional rewards come with their own requirements.
There is also a limited-time offer for qualifying new business policies starting by 31 December 2026. These policies receive a minimum 20% Vitality Money payback on qualifying Discovery and Cogence funds and 10% on eligible third-party funds for the first three policy years, subject to the product terms. Standard payback rules apply after that.