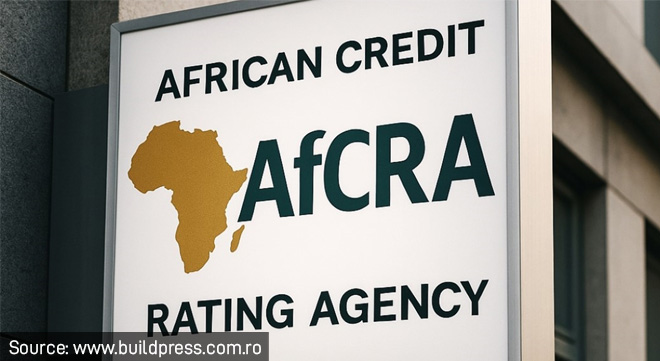
Africa’s first regional credit rating agency is preparing to publish its first ratings by the end of March, but its South African plans have yet to reach the regulator. The Financial Sector Conduct Authority has confirmed that it has not engaged directly with Africa Credit Rating Agency (AfCRA) about operating in the country or seeking regulatory recognition.
“Should AfCRA seek to operate in South Africa or have its ratings recognised for regulatory purposes, any application for registration, recognition, endorsement, or other regulatory approval would be considered in accordance with the applicable legislative and regulatory framework, including the CRS [Credit Rating Services] Act,” the FSCA told Moonstone.
AfCRA was officially launched in Mauritius on 7 October 2026. It aims to provide additional credit assessments of African governments, sub-national entities, companies, and financial institutions, complementing those issued by Moody’s, S&P Global, and Fitch.
The agency was established following an African Union initiative in 2018 and plans to rate African multilateral lenders, including Afreximbank, and private financial institutions.
Read: AfCRA could change how African sovereign risk is assessed
Reuters reported on 3 November that AfCRA’s interim chief executive, Sifiso Falala, said the agency was in talks with 15 African sovereigns and expected to release its first ratings before the end of March.
For those ratings to be used for regulatory purposes in South Africa, AfCRA would need to meet the requirements of the CRS Act and obtain the necessary regulatory approvals.
Three routes to regulatory recognition
The FSCA said the CRS Act establishes mandatory licensing for any person or credit rating agency that performs and issues credit rating services in South Africa.
The Act also makes it mandatory for a regulated person using published credit ratings for regulatory purposes to use only ratings issued or endorsed by credit rating agencies licensed under the Act, or by an external credit rating agency approved by the registrar.
The FSCA identified three options available to AfCRA:
- Apply for registration as a credit rating agency under section 5(1) of the CRS Act.
- Apply for recognition under the FSCA’s equivalence framework for financial markets, published on 3 October 2025. If the regulatory regime in the jurisdiction where AfCRA operates is assessed and recognised as equivalent to South Africa’s framework, AfCRA may apply for exemption from certain requirements of section 5(1) under sections 5(3) and 27 of the Act.
- Seek endorsement of its ratings under section 18 of the Act through a registered South African credit rating agency. The FSCA said AfCRA could consider this route if it has an affiliated or related company licensed as a credit rating agency in South Africa.
In the second route, the FSCA said AfCRA may be recognised as an external credit rating agency if the equivalence and exemption requirements are met.
The CRS Act defines an external credit rating agency as a person that provides credit rating services and is authorised or registered by a regulatory authority to perform similar services under the laws of another country. Those laws must establish a regulatory framework approved by the registrar as equivalent to South Africa’s and must be supervised and monitored by a regulatory authority.
The FSCA said that, for AfCRA’s ratings to be used by South African regulated financial institutions for regulatory purposes, AfCRA would need to be registered under the CRS Act, obtain approval as an external credit rating agency through the equivalence framework and exemption process, or have its ratings endorsed in accordance with section 18.
For AfCRA ratings to be recognised by South African-regulated entities, the FSCA said registration under the CRS Act is required, as well as additional recognition as an External Credit Assessment Institution (ECAI) by the Prudential Authority.
What recognition could mean for institutions
Subject to obtaining the necessary regulatory approvals for registration, recognition, endorsement, and ECAI status, AfCRA’s ratings could be used by South African regulated financial institutions for regulatory purposes, alongside ratings issued by other recognised credit rating agencies.
The FSCA said regulated financial institutions must consider the requirements of section 4(1) of the CRS Act. The extent to which they rely on AfCRA’s ratings would remain a matter for those institutions, subject to applicable regulatory requirements, internal governance arrangements, investment mandates, and risk-management frameworks.
Credit ratings are generally one input into investment and risk-management decision-making and are typically considered alongside internal credit assessments, due diligence processes, and other relevant sources of information.
“The availability of an additional credit rating agency could provide market participants with a different perspective on credit risk, particularly for African sovereigns, corporates, financial institutions, and other issuers,” the FSCA said.
The regulator added that institutions would remain responsible for ensuring their investment and risk-management decisions are supported by robust internal governance, independent analysis, and appropriate risk-assessment processes.
Safeguards for independence and credibility
The FSCA said the CRS Act, together with its subordinate legislation and rules, establishes a robust framework to uphold safeguards for the independence, transparency, and credibility of credit ratings.
The framework includes governance and oversight structures that separate operational and analytical functions from political and commercial influences. It promotes transparent, consistently applied rating methodologies and requires the effective management and disclosure of conflicts of interest.
It also requires proper internal controls, compliance and risk management, as well as clear communication of rating assumptions and actions.
For external credit rating agencies, additional safeguards include recognition that the agency’s home regulatory framework is equivalent to South Africa’s, and effective supervision and enforcement by the regulator in its home jurisdiction.