Small bets, big consequences: How gambling quietly erodes financial resilience
The latest Benchmark research argues that small, recurring gambling losses can compound over time just as powerfully as disciplined investing can build wealth.
The latest Benchmark research argues that small, recurring gambling losses can compound over time just as powerfully as disciplined investing can build wealth.
Sanlam’s Benchmark report argues that improving member outcomes increasingly depends on linking financial advice, healthcare, and risk benefits.
Despite two decades of growing regulation, administration costs have fallen sharply, leaving more retirement contributions invested for members.
While billions have been withdrawn through the two-pot system, Alexforbes says more members are remaining connected to retirement funds long after leaving their employers.
Data from Alexforbes and Sanlam suggests more members are preserving retirement savings, though it is too soon to know whether the shift will last.
COFI’s outcomes-based framework may push governance responsibility beyond trustees and require umbrella funds to prove that members are better off.
The system appears to be changing member behaviour at exit from employment, even as most eligible members continue to make withdrawals.
The products feature tiered fees, contribution boosts, and integration benefits, subject to defined terms and conditions.
The changes include the increase in the annual tax-deduction cap, and new annuitisation and living annuity commutation thresholds.
Treasury also proposes new thresholds at which fund members and living annuitants can commute to a cash lump sum.
The Revenue Laws Amendment Act settles the treatment of provident and provident preservation fund members aged 55 or older on T-day.
The three-year countdown starts only when SARS formally recognises you as a non-resident – a difference of months can affect access and tax outcomes.
The retirement funds correctly refused multiple savings component withdrawals and early access to vested benefits.
Courts and practitioners face contested valuation methods – from present-value drawdowns to post-death capital – with tax and drawdown assumptions driving outcomes.
The two-pot rules redefine ‘pension interest’ at account level, meaning funds must deduct awarded sums proportionally from the savings, retirement, and vested components.
Industry experts say that small, unclaimed pots left behind by members pose a growing challenge that must be managed to protect long-term retirement outcomes.
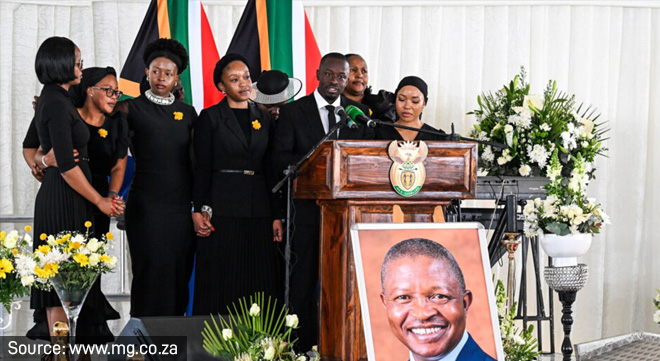
The High Court freezes payouts from the late former Deputy President’s R44.7m annuity amid a family dispute.