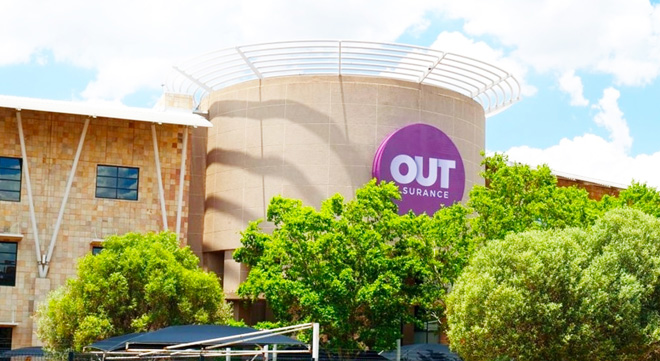
OUTsurance Group Limited’s South African tied broker channel more than quintupled its operating profit to R458 million in the year to June 2026, helping to drive a 43.3% rise in OUTsurance SA’s normalised earnings and an 18.5% increase in group normalised earnings.
The results, released on 10 September 2026, showed divergent performances across the group’s businesses. The South African Personal and Business operations delivered stronger underwriting margins, while a sharp reduction in share-based payment expenses provided a further earnings benefit. Youi Group in Australia continued to grow premiums rapidly, but higher natural-peril claims and deteriorating compulsory third-party, or CTP, claims experience reduced earnings. OUTsurance Life recorded strong new-business growth despite lower reported earnings, while the Irish start-up continued to scale through what management expects to have been its peak-loss year.
The group also raised its ordinary dividend and declared a substantially larger special dividend, supported respectively by higher earnings and the release of surplus capital.
Where the group’s earnings come from
JSE-listed OUTsurance Group Limited (OGL) owns 92.8% of OUTsurance Holdings Limited, the regulated insurance holding company. The listed group reported normalised earnings of R5.605 billion, an increase of 18.5%, while the insurance holding company reported normalised earnings of R6bn, up 20.9%.
The insurance operations comprise OUTsurance SA and OUTsurance Life in South Africa, Youi Group in Australia, and OUTsurance Ireland.
OUTsurance SA was the largest contributor to the insurance holding company’s normalised earnings at R4.196bn, followed by Youi Group at R2.136bn. OUTsurance Life contributed R280m, while OUTsurance Ireland reported a normalised loss of R466m.
South Africa drives earnings as broker channel gains scale
OUTsurance SA’s normalised earnings rose 43.3% to R4.196bn. The improvement reflected better claims experience and lower underlying costs, while a substantial reduction in share-based payment expenses provided a further boost.
The claims ratio improved from 44.6% to 41.9%, with both the Personal and Business segments contributing. In Personal lines, the integrated report attributed the improvement to the stronger rand’s effect on repair costs, lower theft frequency, and continued underwriting improvements. This was despite storms in the Eastern Cape and the Western Cape, which increased natural-peril claims from 4% to 4.6% of net earned premium.
These favourable claims-cost trends also affected premium growth. Group chief executive Visser said during an investor call that lower vehicle accident and theft frequencies, together with the stronger rand’s effect on procurement costs, had caused premium inflation to decouple from consumer inflation. This moderated premium growth but supported profitability.
Management cautioned against assuming that the lower accident and theft frequencies would persist. Visser said vehicle-theft frequency was volatile and difficult to predict, and the improvement in the 2026 financial year came off a very elevated base. High fuel prices may also have contributed to lower accident frequency, which could increase again if fuel prices normalised.
OGL regards expense efficiencies as more predictable than favourable claims trends. Visser said the group did not intend to change its target margins and wanted to pass longer-term cost-efficiency gains on to customers through more competitive pricing. Established expense efficiencies, he said, offered greater certainty about their repeatability.
The final tranche of the legacy Employee Share Option Plan (ESOP) vested in September 2025, reducing the share-based payment expense at OUTsurance SA from R1.289bn to R217m. The plan has been replaced by a Conditional Share Plan (CSP) that is significantly less sensitive to share-price movements and is expected to produce a more stable expense base. On an indicative basis, assuming the legacy plan had been converted to the replacement plan, OUTsurance SA’s cost-to-income ratio improved from 25.1% to 22.2%.
Within the South African operation, OUTsurance Business increased gross written premium (GWP) by 12.1%, from R3.018bn to R3.382bn, while operating profit rose 49.8%, from R697m to R1.044bn. Its cost-to-income ratio improved from 31.8% to 28.7% as the broker channel generated economies of scale despite continued expansion of the sales force. Its claims ratio improved from 46.7% to 41.2%, reflecting a maturing book, positive claims-frequency trends, and underwriting improvements.
OUTsurance Brokers, the tied-agency channel within OUTsurance Business, largely drove the division’s premium growth and is now its largest source of revenue. The channel focuses primarily on growing OUTsurance’s commercial market share through face-to-face distribution, but it also distributes personal-lines products on behalf of OUTsurance Personal.
The broker channel’s operating profit increased more than fivefold, from R87m to R458m, whereas the direct Business channel’s operating profit declined 3.9% to R586m. Visser said the difference between the division’s premium and profit growth reflected the broker channel’s progression from around break-even to its target margin. He said further improvement in the channel’s cost ratio remained possible as it continued to scale.
Although OGL does not disclose the split between broker-generated and directly generated premiums in Personal lines, management said the broker channel was making a meaningful contribution to OUTsurance Personal’s premium growth.
Personal lines remained the larger operation. OUTsurance Personal increased GWP by 6% to R10.96bn and operating profit by 14.4% to R4.29bn. The faster growth in OUTsurance Business therefore reflected both the expansion of the broker channel and its progression to stronger margins.
OGL sees further scope to expand because its market shares in the face-to-face and Business segments remain relatively low. Visser said growth would remain subject to underwriting discipline. The group was focused on profitability and would grow only as quickly as circumstances and its ability to execute allowed.
Youi grows premiums but claims pressure earnings
Youi Group remained the group’s largest property and casualty premium business and continued to expand, but higher natural-peril claims and weaker CTP results offset much of the benefit.
Excluding the discontinued BZI broker channel, GWP rose 21.3% to A$2.241bn. Normalised earnings nevertheless declined 6.7% to R2.136bn.
Natural-peril losses increased from 9.8% to 11.7% of net earned premium after significant storm events, particularly in the first half. Youi Group’s claims ratio rose from 58.5% to 62.2%.
Youi Direct accounted for most of the premium growth, increasing GWP by 21.2% in Australian dollars. Its operating profit declined 2.4% in Australian dollars as higher claims, including those arising from adverse weather, weighed on the result.
The full-year result masked a substantial recovery in the second half. Visser said Youi Group had been well behind the previous year at the half-year stage because of high natural-peril losses but recovered much of the lost ground during the second half.
Visser said the group had experienced less volatility than during some recent periods with heavy natural-peril losses. He attributed this to improved pricing and underwriting, unchanged nominal reinsurance attachment points during a period of strong growth, and greater product and geographical diversification in Australia. The latter included writing more business outside areas with higher natural-peril exposure. However, he cautioned that results could remain volatile over six-month periods, although the effects tended to even out over a full year.
Youi CTP, which provides compulsory third-party motor insurance in New South Wales and South Australia, also deteriorated sharply. Its operating loss widened from A$11m to A$29m, and its claims ratio increased from 100.3% to 117.4%.
The group attributed the deterioration mainly to an increased frequency of common-law claims in New South Wales. Management said these claims generally also had a higher severity than other settled claims. The adverse experience affected current-year claims and required estimates for claims from previous years to be strengthened. Corrective pricing action contributed to slower growth in the second half.
Visser said profitability had also weakened across the broader CTP market. However, OGL continued to regard the segment as strategically important over the longer term, both as part of its ambition to become a major Australian insurer and as a potential source of diversification and growth at the appropriate margin.
The BZI broker channel, which ceased writing new business on 1 July 2025, produced an operating profit of A$30m during its run-off. The final policies expired on 30 June 2026.
Life delivers strong new business despite lower reported earnings
OUTsurance Life’s normalised earnings fell 19.8% to R280m against a favourable prior-year base. The 2025 result benefited from favourable assumption changes and the reversal of a loss component on a defined product set.
New-business measures moved strongly in the opposite direction. The value of new business increased 41.5% to R457m, reflecting product simplification and accelerated growth in the Direct channel. The new-business margin improved from 22.1% to 23.7%, benefiting from cost efficiencies and scale.
Most of the growth in the value of new business came from Life Direct, despite the channel’s operating profit declining 31.9% to R372m. Management said the profit comparison was distorted by a R101m adverse swing in the effect of yield movements, from a R43m gain in 2025 to a R58m loss in 2026.
The Funeral Partnership channel’s operating profit increased 88.5% to R98m, which management attributed to continued strong operational execution.
Ireland builds scale through expected peak-loss year
OUTsurance Ireland increased GWP from €14m to €41m in its second full year. Its operating loss widened from R448m to R489m.
Visser said the Irish operation was being scaled cautiously because a new insurer starts without its own body of underwriting data and must balance the need to gain scale against the risks of anti-selection and pricing errors. Expanding too quickly could amplify those errors, he said.
The group said the 2026 operating loss represented the peak of the Irish business’s expected loss curve, supported by a decline in monthly losses during the second half. OUTsurance Ireland continues to target monthly break-even during the 2029 financial year.
The claims ratio excluding the onerous-contract provision was 73.5%. The group said the lower onerous-loss expense reflected improved economies of scale and a lower claims ratio, providing early signs of prudent risk selection and adequate pricing.
The estimated total capital required to establish the Irish operation has been revised from the original business-plan figure of €160m to €190m. Of this, €120m had been provided by 30 June 2026, while the remaining €70m is expected to be funded incrementally from retained earnings over the next four years.
Higher earnings and surplus capital support larger dividends
The stronger earnings result supported a higher ordinary dividend. Its 22.7% increase exceeded the growth in group earnings because OUTsurance SA, which operates at a higher payout ratio than Youi Group, contributed a larger share of earnings.
A final ordinary dividend of 170.8 cents brought the full-year ordinary dividend to 291.5 cents a share, representing a payout ratio of 80.5%, compared with 77.6% in 2025. A final special dividend of 87.5 cents took the full-year special dividend to 117.8 cents. Combined ordinary and special dividends totalled 409.3 cents a share, compared with 270.7 cents in the previous year.
The special dividend was supported by surplus capital released through the replacement of the capital-intensive ESOP and other capital-optimisation projects in OUTsurance SA, the run-off of Youi Group’s BZI book, and a distribution of surplus capital held in RMI Treasury Company.