Dealers in precious metals and precious stones could qualify as accountable institutions when they sell or trade an individual metal or stone, or a bundle treated as a single good, valued at R100 000 or more, under draft guidance issued by the Financial Intelligence Centre (FIC).
Draft Public Compliance Communication 126 (PCC 126), issued for consultation on 30 September 2026, sets out the FIC’s proposed interpretation of how item 20 of Schedule 1 to the Financial Intelligence Centre Act (FICA) applies to dealers operating across the precious-metals and precious-stones supply chains. Item 20 designates dealers in high-value goods as accountable institutions.
The draft says a dealer may be a natural or juristic person, South African or foreign, operating at various points in the supply chain. These include miners, manufacturers, beneficiators, refiners, wholesalers, retailers, importers, exporters, intermediaries, brokers, polishers, cutters, jewellery manufacturers, and buyers or sellers in secondary markets.
It does not treat every person dealing in precious metals or stones as an accountable institution. The relevant activity must fall within its proposed interpretation of a dealer in precious metals or a dealer in precious stones and meet the applicable value threshold.
How the R100 000 threshold would apply
The FIC says “precious” in this context means that a particular metal or stone, or a bundle sold or traded as a unit, is valued at R100 000 or more. This value is the amount for which the good is sold or traded.
Separate goods are not aggregated merely because their combined value reaches the threshold. However, goods sold or traded together as one bundle are assessed according to their combined price.
For example, a diamond dealer who trades a set of diamonds for R130 000 in the ordinary course of business would be a high-value goods dealer because the set constitutes one bundled good.
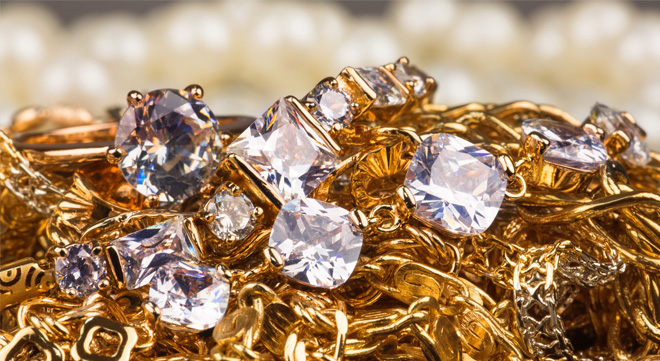
The metals covered by the draft include gold, silver, platinum, palladium, rhodium, ruthenium, iridium, and osmium. They may take various forms, including bullion, bars, ingots, and numismatic coins such as Krugerrands.
Diamonds are classified as precious stones. The draft also applies to semi-precious stones such as rubies, sapphires, tanzanite, and emeralds where a transaction exceeds R100 000.
Separate registration may be required for each authorisation
Draft PCC 126 focuses particularly on licences and permits issued by the South African Diamond and Precious Metals Regulator (SADPMR).
These include precious-metals refining and beneficiation licences, jewellers’ permits, import permits, export approvals, minted-bar licences, diamond beneficiation licences, diamond-dealer licences, temporary diamond buyers’ permits, and diamond trading-house licences.
Holding an authorisation does not, by itself, make the holder an accountable institution. The FIC says a person must register as a dealer in precious metals or stones for each permit or licence under which the requirements of item 20 are met.
It gives the example of an entity holding a precious-metals jeweller’s permit, a precious-metal import permit, and a licence to deal in unpolished diamonds. If the activities conducted under all three authorisations meet the threshold, the entity must make three separate registrations on the FIC’s registration and reporting platform.
Krugerrand dealers have a dedicated sub-category on the platform. Other numismatic-coin dealers register under the dealers in precious metals category.
The FIC says it sought input from the SADPMR during the drafting process.
The draft does not cover criminal conduct involving illegally held or traded precious metals and stones. The consultation note says such offences are governed primarily by the legislation regulating precious metals, precious stones, and mining.
When transactions must be reported
The R100 000 amount is a classification threshold, not a reporting threshold. Meeting the applicable threshold brings a dealer within the scope of item 20, subject to the other requirements set out in the draft.
A report must be submitted when:
- a transaction or activity is suspicious or unusual under section 29 of FICA;
- a cash transaction amounts to R50 000 or more under section 28; or
- property, including precious metals, stones, or funds, is linked to a person designated on the targeted financial sanctions list under section 28A.
The section 29 obligation is not limited to registered accountable institutions or transactions above a particular value. The draft says any business entity operating for profit must report a transaction that it finds suspicious or unusual, regardless of the amount.
Deliberately splitting transaction amounts to evade the R100 000 threshold is considered structuring, and businesses must consider whether a section 29 report should be filed.
The draft also distinguishes between industry bodies that conduct transactions and those that merely become aware of suspicious transactions involving their members. A body that operates for profit and enters transactions may have a section 29 obligation; one that merely becomes aware of suspicious transactions involving members is encouraged to register and submit a voluntary disclosure report through the goAML platform.
Other accountable institutions processing dealers’ transactions must assess whether the activity is consistent with the client’s profile and submit a section 29 report if they find a transaction suspicious or unusual.
Dealers must assess sector and client risks
Draft PCC 126 requires dealers to follow a risk-based approach to money laundering, terrorist financing, and proliferation financing.
As part of customer due diligence, a dealer should establish whether a client who is required to be registered, licensed, or permitted holds the necessary authorisation. Its absence may be a risk indicator.
Dealers must take reasonable steps to establish the source of precious metals or stones and where the client is selling them. When a client is buying these goods, the dealer must also determine the source of the funds.
Entity-wide risk assessments must consider relevant national and sector risk assessments. Geographic considerations include connections to:
- countries subject to United Nations Security Council sanctions;
- jurisdictions on the Financial Action Task Force’s grey list or blacklist;
- high-secrecy jurisdictions and alleged or known tax havens;
- countries with weak governance, law-enforcement, regulatory, or anti-money laundering systems;
- cash-based economies and jurisdictions using informal banking systems;
- countries with high levels of organised crime or corruption;
- countries with high levels of predicate offences such as illegal mining or rough-diamond smuggling; and
- jurisdictions that inadequately regulate their precious-metals and stones sectors.
Enhanced due diligence should be considered for clients based in high-risk geographic areas.
For rough diamonds, the draft identifies as a risk factor whether the source country participates in the Kimberley Process and has measures to monitor compliance.
Although participation in an internationally accepted certification scheme may reduce certain risks, it does not justify automatically classifying every associated transaction as low risk. Client-specific factors must still be considered.
Consultation closes on 16 October
Draft PCC 126 should be read together with PCC 58, issued in March 2024, and the FIC’s sector risk assessments for dealers in precious metals and stones.
The draft states that FIC guidance is authoritative and must be considered when interpreting FICA or assessing compliance. Once PCC 126 is finalised, an institution that departs from the guidance would have to demonstrate that it complied with the relevant statutory obligation in an equivalent manner.
Enforcement action may follow where an institution has not complied with FICA in an area covered by the guidance.
Comments must be submitted through the FIC’s online consultation form by close of business on Friday, 16 October 2026.