A manufacturer deciding where to build its next plant will look at more than the cost of production. It will also consider whether it can sell its products into its biggest markets at competitive prices.
That is where the loss of South Africa’s preferential access to the US market could have consequences that extend beyond the additional tariffs exporters will face.
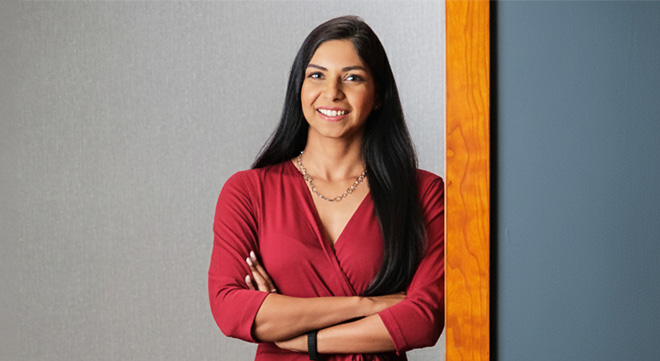
Sanisha Packirisamy (pictured), chief economist at Momentum, says the effect on investment could ultimately outweigh the immediate tariff cost.
“We think the effect on investment could ultimately outweigh the immediate tariff cost. Companies commit capital based on the returns they expect over many years, so uncertainty about access to export markets can raise the hurdle rate that a project must clear,” she said.
“It could also prompt a multinational to place production somewhere else.”
Washington has announced its intention to remove South Africa’s eligibility for the African Growth and Opportunity Act (AGOA) from 1 January 2027. The decision will end preferential tariff treatment for qualifying South African goods, but exporters will still be able to sell into the US market.
“We view this primarily as a limited, incremental trade shock, though one that also signals where the bilateral relationship may be heading,” Packirisamy says.
South African government figures indicate that AGOA-eligible goods accounted for about 10% of the country’s exports to the US in 2025, and only around 1% of its total merchandise exports.
“The added economic hit should therefore be far smaller than the damage already caused by the wider tariff measures,” she says.
But the consequences for individual businesses could be more pronounced, particularly where companies depend on preferential access to remain competitive.
Which companies face the greatest exposure?
Investors need to look beyond how much revenue a company earns from the US.
“When assessing listed companies, investors should look at how much of their South African output is shipped to the US, which of their products still rely on AGOA, and how readily buyers could move to other suppliers,” Packirisamy says.
“Revenue from the US on its own is a poor gauge of exposure, especially for companies that manufacture offshore or sell goods that already enter the US duty-free under ordinary rules.”
A company that generates substantial US revenue may face little direct impact if its products already enter the country duty-free. Another company with a smaller US revenue contribution could face greater pressure if its products depend on AGOA preferences and its customers can readily switch to competing suppliers.
“The greatest exposure is likely to be among agricultural exporters and producers of processed foods, along with certain manufacturers and the businesses that supply them,” Packirisamy says.
The automotive sector has traditionally gained from AGOA, but other US tariffs have already stripped away much of that advantage.
Many of the businesses directly affected are unlisted. The consequences for particular industries and communities could be larger than anything visible in movements on the equity market.
Who absorbs the additional tariff?
Estimates from the Bureau for Economic Research and Business Unity South Africa suggest that losing AGOA would increase US import tariffs on affected South African goods by around three to four percentage points on average, although the increase would vary by product.
This is not a new tariff applying to every South African export.
US importers pay the duties, but the cost can be spread across importers, consumers and South African suppliers.
“Buyers might push for lower export prices, accept thinner margins themselves, or pass the increase on through higher selling prices,” Packirisamy says.
“Which of these happens depends on the terms of existing contracts, the presence of competing suppliers and how easily customers can switch to another product.”
Exporters that cannot pass the additional cost on to customers could face softer demand, lower prices and reduced production volumes, putting pressure on margins and earnings.
Suppliers and logistics providers may also see order volumes fall.
“A weaker rand could soften the blow to rand-denominated revenue, but imported inputs and currency hedging arrangements may limit how much of that benefit is actually felt,” Packirisamy says.
Redirecting exports to other markets is possible, but it takes time and may come with lower prices or additional costs.
“Entering new markets means finding customers, building distribution networks, securing regulatory approvals, and meeting different product specifications,” she says.
What will show whether companies are changing course?
Packirisamy says the effects on investment may emerge gradually, as projects are postponed, scaled back or built outside South Africa.
“Investors should monitor whether companies turn announced capital expenditure into real spending, win new export contracts and keep their production mandates,” she says.
“Management comments on customer orders, capacity utilisation, hiring, and project approvals will indicate the level of corporate concern.”
These developments could offer a better indication of how companies are responding than the immediate reaction in their share prices.
“Losing AGOA status is unlikely, on its own, to justify a large and lasting repricing of South African financial assets,” Packirisamy says.
“Direct export exposure is limited, and the prospect of exclusion had already been widely debated in markets.”
This may explain why the rand had not moved much on the day following the announcement.
But Packirisamy notes that the currency could weaken, and bond yields could climb if investors interpret the decision as a precursor to wider restrictions or a decline in investment, particularly if diplomatic relations deteriorate further.
“Losing AGOA status does not, by itself, mean broader investment or financial restrictions are coming,” she says. “But this is not a positive development for the relationship between the US and South Africa.
“Over the coming six to 12 months, investors should track product-level export volumes, company earnings guidance in relation to the US, capital expenditure outlays, and any headlines on new market access,” she says.
Foreign purchases of local bonds and equities, sovereign credit spreads, and the rand’s performance against comparable emerging market currencies will also provide useful indicators.
Packirisamy says the risk would be easier to contain if government dialogue continues and delivers visible progress on market access.
“Improvements at home in ports, rail, electricity supply, and municipal outcomes would also make South Africa a more attractive place to invest, whatever direction US policy takes,” she says.