Financial planners may respond to client inaction with another projection, a clearer explanation, or more information about the consequences of doing nothing. But information will not necessarily help when the client is not ready to change.
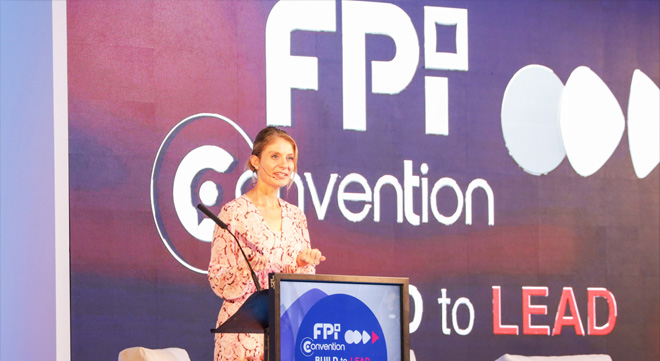
Sonya Lutter, a Certified Financial Planner® professional, told delegates at the FPI Professionals Convention on 8 October 2026 that planners should pay closer attention to the relationships, beliefs, and pressures influencing clients’ decisions. They should also consider whether clients are ready to act and can identify a manageable next step.
Lutter is the director of Financial Health and Wellness in the School of Financial Planning at the Texas Tech University College of Human Sciences.
She organised her approach to the psychology of financial planning into three parts: think systemically, talk therapeutically, and plan intentionally.
The purpose is not to turn financial planners into therapists. It is to help them understand the influences surrounding a financial problem, communicate in a way that suits the client’s readiness for change, and translate advice into achievable action.
Think systemically: look beyond the client
Financial planning may focus on an individual or household, but decisions are often shaped by a much larger network of relationships.
Lutter said planners should listen not only to what clients say but also to how they communicate. Tone, body language, and the interaction between people in a meeting may reveal information that their words alone do not convey.
This may be particularly relevant when a couple consults a planner. One person may have initiated the engagement and therefore be more involved in the conversation. The planner should notice how the other responds as particular subjects or words arise and look for opportunities to bring that person into the discussion.
These observations should not be treated as proof of what someone is thinking. Instead, Lutter encouraged planners to become curious about what they notice.
A planner could say, “I notice you became quiet when we started discussing this,” and invite the client to explain. This gives the person room to correct the observation or provide information that has not yet emerged, without being accused of disengagement or indifference.
Lutter suggested using prompts such as “I notice”, “It seems”, and “Tell me”. She said that “Tell me how you came to this decision” could produce a different conversation from “How did you make this decision?” The former invites an explanation without making the exchange feel like an interrogation.
She challenged planners to hold a 10-minute conversation in which they learn something new without asking a single question, relying instead on observations and prompts.
Thinking systemically also involves identifying the people and relationships that affect a client’s choices, including those who are not present in the meeting.
Lutter said she starts constructing a genogram when she first speaks to a client. Similar to a family tree, it records the connections between people, organisations, and other significant parts of the client’s life.
She uses the visual map to organise the names and relationships that emerge over successive meetings. It may record close family connections, estrangement, family-business relationships, and people whom the client supports or wants to include in an estate plan.
Lutter illustrated its use with a family in which a grandfather had a close relationship with his minor granddaughter. The child’s father was seldom discussed and appeared to have been cut off from the family, although the reason was unknown. This became relevant when the grandparents considered how to provide for the child and whether her father should have any role.
The example shows why an apparently technical estate-planning question may not be understood fully without considering the family relationships behind it.
A planner can retain the genogram as an internal reference, particularly when working with complex or multigenerational families. Where appropriate, it can also be shown to the client to check whether it accurately reflects the relationships described.
Talk therapeutically: establish readiness for change
Understanding the influences surrounding a decision does not mean the client is prepared to make it.
Lutter used the expression “talk therapeutically”, but she did not propose that financial planners should practise therapy. They do not have to resolve a client’s grief, relationship difficulties, or other personal problems.
They can, however, acknowledge what the client is experiencing and consider whether the person can process financial information at that time. Someone going through a divorce, for example, may need financial guidance, but the planner should not attempt to act as a marriage counsellor.
Drawing on motivational interviewing, Lutter said planners should identify a client’s readiness for change and adapt their communication accordingly. She distinguished between people who are not yet considering change, those weighing its costs and benefits, those preparing to act, and those already taking action.
She suggested asking clients, on a scale from zero to ten, how important it is to achieve a particular goal or how ready they are to make the required change. The number indicates where the conversation should begin.
Someone at the lower end of the scale may not believe there is a problem. One member of a couple may want change while the other thinks the household’s finances are satisfactory. An adult child may attend a meeting only because a parent insisted. The planner may also be treating a change as necessary before establishing whether the client considers it important.
The instinctive response may be to provide charts showing where the client could be in 20 years, brochures explaining the options, or warnings about the consequences of failing to act.
According to Lutter, additional information is unlikely to move a person who does not yet see a reason to change. At this stage, the planner should focus on external motivation by helping the client consider who would be affected if nothing changed.
A person who is contemplating change may recognise its benefits but believe other priorities must come first. Rather than immediately trying to overcome the objection, the planner can reflect the discrepancy.
The planner might say: “I hear that you can see the benefits of changing, but it does not feel worthwhile to you right now.”
The client may respond that the change is worthwhile but explain what must happen first. This identifies the obstacle and provides a basis for addressing it.
Although this approach may appear slower than proceeding directly to advice, Lutter argued that attentive listening and accurate reflection can help a client move closer to action.
Projections, explanations, and educational material become more useful when the person is preparing to act. The point is not to withhold relevant information but to recognise that it is not the solution to every form of inaction.
Readiness may also be affected by the meaning someone attaches to money.
Lutter suggested asking clients to complete the sentence: “Money is …”
A person may describe money as freedom or associate it with greed or another deeply held belief. If the answer is “freedom”, the planner could respond, “Tell me why money is freedom for you.” If it is negative, the client could be asked how they would prefer to complete the sentence in an ideal world.
Families do not always speak openly about money. Yet people entering a planner’s office may be expected to disclose their circumstances, priorities, and fears to someone they do not know well. Exploring their underlying beliefs can provide a more informed starting point for the discussion.
Plan intentionally: make the next step manageable
A client can accept a recommendation but fail to implement it because the action feels too large.
Lutter illustrated this with a proposal to increase contributions to an employer-sponsored plan. The instruction may appear straightforward to the planner, while the client may not even know whom to contact to make the change.
The solution is to reduce the recommendation to what Lutter described as the “teensiest, tiniest step”.
If a client rates their readiness at four out of ten, the immediate objective need not be moving them to ten. The planner can ask what would take them from four to five.
In Lutter’s example, that first step may simply be identifying the appropriate contact person. Finding that person together removes an obstacle and begins the implementation process.
She illustrated the principle with her childhood experience of being expected to climb a rope during physical education classes. The rope was uncomfortable, she was uncertain whether it was secure, and her classmates were watching. She would touch it and stop, which counted as a failed attempt.
The outcome might have been different if the task had been divided into stages. She could first have seen how the rope was secured, handled it while it was on the ground, or practised in front of a smaller group.
Similarly, a client may resist a recommendation not because they oppose the objective but because the distance between their present position and the requested change appears too great.
Intentional planning also requires planners to consider what they bring into the meeting.
Lutter said a planner’s stress can affect the interaction. A hurried, tense, or distracted adviser may make an already difficult conversation harder. A client preoccupied by something that happened immediately before the meeting may also be unable to concentrate on a long-term decision.
Instead of pushing ahead with the agenda, the planner can ask what is on the client’s mind. A brief opportunity to explain, write something down, or attend to an urgent matter may allow the person to re-engage.
Lutter also encouraged planners to consider how they frame questions. Asking what keeps clients awake at night about their financial situation directs attention towards worries. Asking what excites them about it prompts them to consider more positive possibilities.
That does not mean difficult subjects should be avoided. Risks, fears, and financial distress may require direct discussion. The point is to choose the wording deliberately and recognise that it can shape the conversation.
Lutter advised planners to begin with one technique rather than attempting to implement her entire framework at once.
They could map the important relationships in a client’s financial life, ask the person to complete the sentence “Money is …”, or replace an interrogative question with “I notice”, “It seems”, or “Tell me”. They could also take an unimplemented recommendation and identify the smallest action needed to move it forward.
Technically appropriate advice remains essential. But its value also depends on whether the planner understands the influences affecting the client, communicates at the appropriate stage, and makes the path to action manageable.