The COFI shift that could reshape customer disclosure
Section 31 of the Bill offers a window into a conduct framework built around relationships, outcomes, and ongoing institutional accountability.
Section 31 of the Bill offers a window into a conduct framework built around relationships, outcomes, and ongoing institutional accountability.
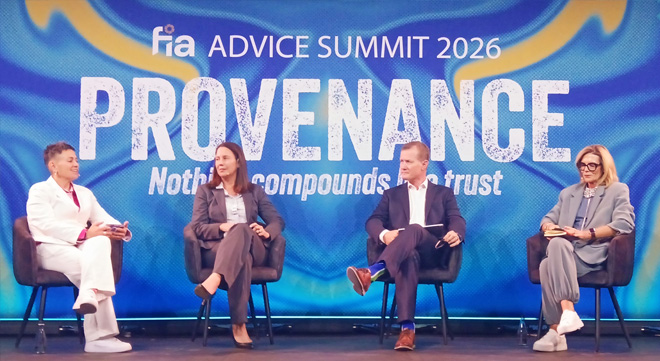
The FSCA’s Lezanne Botha explains why signed forms and completed disclosures are not enough, and what evidence can show that advice was suitable and customers were treated fairly.
The FSCA plans to consult on its relicensing approach and publish it about six months before the relevant provisions take effect.
The Authority’s three-year roadmap also outlines upcoming reforms affecting financial markets, retirement funds, payment services, and cross-sector regulation.
COFI’s outcomes-based framework may push governance responsibility beyond trustees and require umbrella funds to prove that members are better off.
A top priority is supporting National Treasury in finalising COFI and rolling out the themed frameworks.
The ‘imminent’ COFI Bill will introduce the licensing of retirement funds (including public sector funds), stricter board member standards, and enhanced oversight of contributing employers.
A failure to comply with specific BEE thresholds outlined in transformation plans could lead to the Authority withholding licences.