
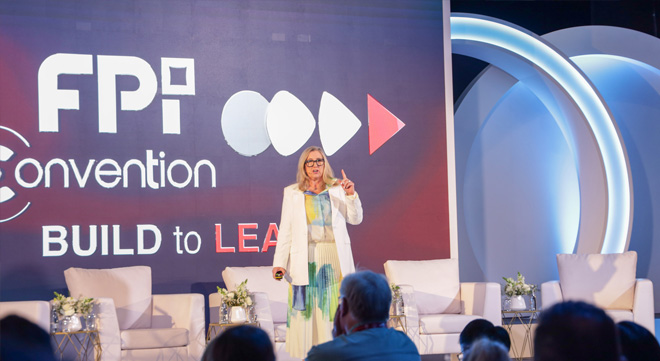

A technically sound financial plan may still fail if the adviser does not understand the experiences, emotions, and motivations influencing the client’s behaviour.
This was one of the central messages from Kim Potgieter (pictured) CFP®, the managing director and head of life planning at Chartered Wealth Solutions, during a presentation at the FPI Professionals Convention in Cape Town on 7 October 2026.
Potgieter said advisers should take time to understand a client’s life before recommending how the client’s money should be invested.
At Chartered Wealth Solutions, this involves holding a two-hour life-planning meeting before discussing investments.
“We will not invest anybody’s money until we understand their life,” she said.
The meeting explores the client’s aspirations and relationship with money, including why the client may not implement or adhere to a financial plan.
Advisers can construct plans of which they are technically proud, but clients will not necessarily implement them or stick to them. The process takes time, Potgieter said, but the foundation it creates is more important than the time it requires.
Find the motivation behind the stated goal
A client’s initial request does not always reveal what the client ultimately wants to achieve.
Potgieter illustrated this with the example of a client in her late 40s. The client, who was a single mother with two young children, wanted a financial plan that would enable her to buy a holiday home.
Potgieter explored why the holiday home was important to the client before finalising the plan.
The client’s underlying goal was to spend more time with her children and create shared experiences. Projections showed that she would have enough money to buy the property by the time the children were 18, when they would probably be leaving for university.
Because Potgieter understood why the client wanted the property, the plan changed. Rather than waiting years to buy it, the revised plan enabled the client to begin creating those experiences with her children immediately and to work less intensively.
The client had asked for an asset, but what she wanted was time with her children. The most suitable plan was not necessarily the one that led to property ownership.
Potgieter said clients are more likely to adhere to plans they have helped to formulate. Giving them time to express their goals helps to make the resulting financial plan their own, rather than one based on the adviser’s assumptions.
Another question she asks is: “What will your next chapter look like if it turns out well?”
Clients may not have an immediate answer. Potgieter said advisers can guide them as they become more confident and their goals become clearer over successive meetings.
Ask clients about their relationship with money
Potgieter said clients bring established beliefs, habits, and associations with money into the planning process. Advisers need to understand these influences if they want to help clients change their behaviour and remain committed to their plans.
She suggested five questions advisers can ask:
- What is your first memory of money?
- What lessons about money did you hear while growing up?
- How do those experiences affect your relationship with money today?
- Which of your financial habits serve you, and which do not?
- What does money truly represent to you?
Clients may associate money with freedom, security, or love. They may also have grown up hearing statements such as “money doesn’t grow on trees”, “money’s the root of all evil”, or “easy come, easy go”.
These messages can continue influencing financial behaviour in adulthood. Understanding them can help an adviser to identify why a client may find a recommended change difficult and communicate the advice more effectively.
Listen for the concern beneath the behaviour
Advisers should avoid responding only to a client’s visible behaviour. For example, a client who calls angrily when markets fall or after an error involving the client’s account may feel overwhelmed, anxious, or afraid.
Potgieter encouraged advisers to remain curious about what lies beneath the immediate response. They can identify the emotion they believe they are observing and reflect it back to the client, giving the client an opportunity to confirm or correct that interpretation.
Responding only to the anger can distract from the underlying concern. Financial decisions do not occur separately from emotion, particularly when clients face uncertainty, fear, or anxiety.
Do not take over the client’s story
Potgieter cautioned advisers against responding to a client’s difficult experience by immediately recounting a similar experience of their own.
An adviser may intend to demonstrate understanding when a client discusses a traumatic event, hardship, or another difficult experience. But introducing the adviser’s own story can make the client’s experience seem less significant.
Potgieter described this as an “empathy miss”. The adviser believes sharing a comparable experience will build a connection but risks shifting attention away from the client.
Advisers do not need to have undergone the same experience to acknowledge the emotions involved. By naming the emotion, they can help clients to feel seen and heard.
During the presentation, Potgieter showed a video about the distinction between empathy and sympathy. The video cautioned against trying to fix a difficult situation immediately or place a positive interpretation on a painful experience.
Potgieter encouraged advisers to apply this understanding of empathy in client conversations. Her suggested approach was: “I’m in it with you. I’m not here to fix you. I’m not here to feel it for you. I’m here to feel with you and let you know that you’re not alone.”
Deep listening requires more than remaining silent until it is time to present a recommendation.
Potgieter proposed that the client should speak for about 80% of a meeting and the adviser for about 20%. In practice, she said, the ratio is often reversed because advisers are too eager to reach the point where they give advice.
“Our clients don’t hear us until we hear them,” she said.
Listening should not be treated merely as a preliminary stage before the adviser presents a solution. The purpose of the 80/20 guideline is to give the adviser a fuller understanding of the client before offering advice.
Examine the biases you bring to the meeting
Advisers bring their own histories and beliefs about money into client meetings. Potgieter said they need to understand their triggers and recognise when judgement is influencing their thinking. Without self-awareness, they may give advice through the lens of their own perspective.
She gave the example of a younger financial planner who became frustrated with clients who continued giving money to their adult children, even though the parents were at risk of exhausting their own resources.
The planner had been expected to earn her own money when she was young. Her upbringing influenced her reaction to the clients’ decision to continue supporting their children.
Potgieter said advisers can provide financial advice while recognising that clients have their own circumstances, values and framework for making decisions.
The example illustrated how an adviser’s personal experiences can influence their judgement. Advisers should distinguish between a professional concern about a client’s finances and a personal reaction shaped by their own experiences and values.
Boundaries can strengthen trust
Building a close relationship with a client does not mean agreeing to every request.
Potgieter said advisers need appropriate professional boundaries. Saying yes to everything can eventually result in an adviser delivering less than was promised.
Trust also requires reliability, accountability when mistakes occur, and the integrity to tell clients something difficult rather than simply agreeing with them.
Clients are not the adviser’s friends, she said. The relationship should remain professional but caring, and advisers also need to look after themselves.
Support clients through major transitions
The need for technical competence and human understanding often converges when clients face significant life transitions.
Retirement, retrenchment, divorce, and financial difficulty can have emotional consequences and may affect how clients see themselves and their future.
A person approaching retirement, for example, may have spent decades deriving a sense of value from being a provider. The transition can therefore involve more than establishing whether the client has accumulated enough capital.
Advisers can assist clients by asking questions and providing resources. Potgieter suggested introducing clients to people who have undergone similar transitions or recommending relevant articles and podcasts.
She said advisers need to learn to sit with the discomfort and uncertainty surrounding these transitions while helping their clients through them.
“I believe that technical expertise helps us understand what is financially possible. Human capabilities help us understand what is personally meaningful. Trust is built when we bring the two together,” Potgieter said.


