
Serious financial harm not enough to secure removal of SAFPS listing
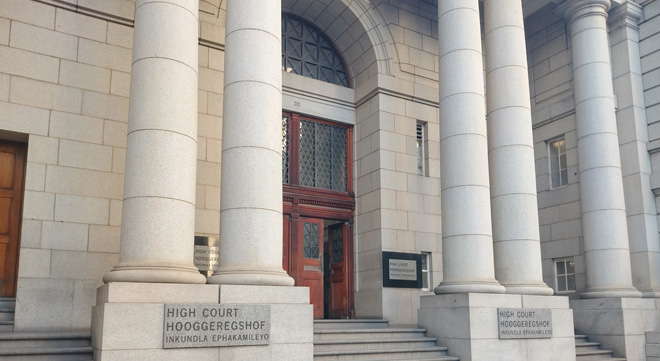
The High Court recognised the potentially serious prejudice to the applicant but found that his evidence did not meet the threshold for interim relief.
The High Court recognised the potentially serious prejudice to the applicant but found that his evidence did not meet the threshold for interim relief.
A fraud-related cancellation almost 15 years earlier cost the policyholder his tornado claim because he failed to disclose it when applying for cover.
Determination says a ‘reasonable broker’ would supplement a bulk email with an email or phone call to ensure the client is aware of new conditions.
Applicants must fully disclose all relevant information during underwriting, even if it was divulged in past applications.


The Ombud failed to investigate key facts around the broker’s alleged negligence in communicating an essential policy requirement.
The court ruled that MiWay’s expert analysis relied too heavily on assumptions, while overlooking the driver’s account that he swerved to avoid a dog.
When seeking compensation from an insurer because of alleged third-party negligence, the best course of action is to pursue the matter in court, the National Consumer Tribunal says.
The consultant should have provided the available options to the insured and left it to the insured to decide which category best suited his business.


